Second VA Loan, Assumption, or Sell: The Entitlement Math Behind Your Next PCS From JBSA (2026)
LAST UPDATED: SEPTEMBER 11, 2026 | BY CHRISTOPHER BEAL, U.S. ARMY VETERAN & REALTOR
Second VA Loan, Assumption, or Sell: The Entitlement Math Behind Your Next PCS From JBSA (2026)
Key Takeaways
- You do NOT lose your VA loan benefit when you PCS from San Antonio. Full entitlement carries no VA loan limit at all. A county limit only enters the math once part of your entitlement is still tied to a home you are keeping, and how much room is left then depends on the Entitlement Charged shown on your COE and the one-unit limit in the county you are buying in.
- A $300,000 VA loan typically charges $75,000 of entitlement. Against an $832,750 one-unit limit at the next duty station that leaves about $133,187 of remaining bonus entitlement, supporting roughly $532,750 with no down payment. Use the Entitlement Charged figure on your own COE rather than an estimate, and remember the lender still has to approve the loan and the appraisal still has to support the price.
- Letting a civilian buyer assume your low-rate VA loan freezes your entitlement until that loan is paid off. Only a substitution of entitlement by an eligible veteran buyer releases it.
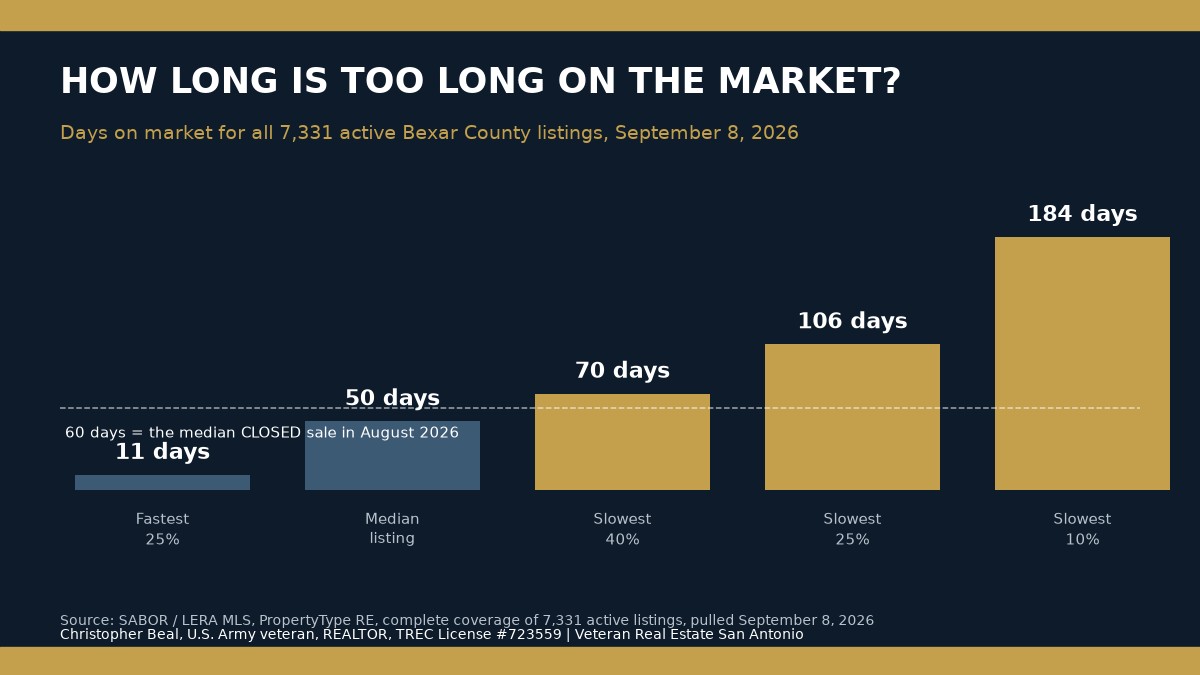
- Selling and paying the loan off in full is one of three VA restoration routes, but budget the timeline: SABOR data through mid-2026 shows homes averaging 77 days on market before the 30 to 45 day closing period even starts.
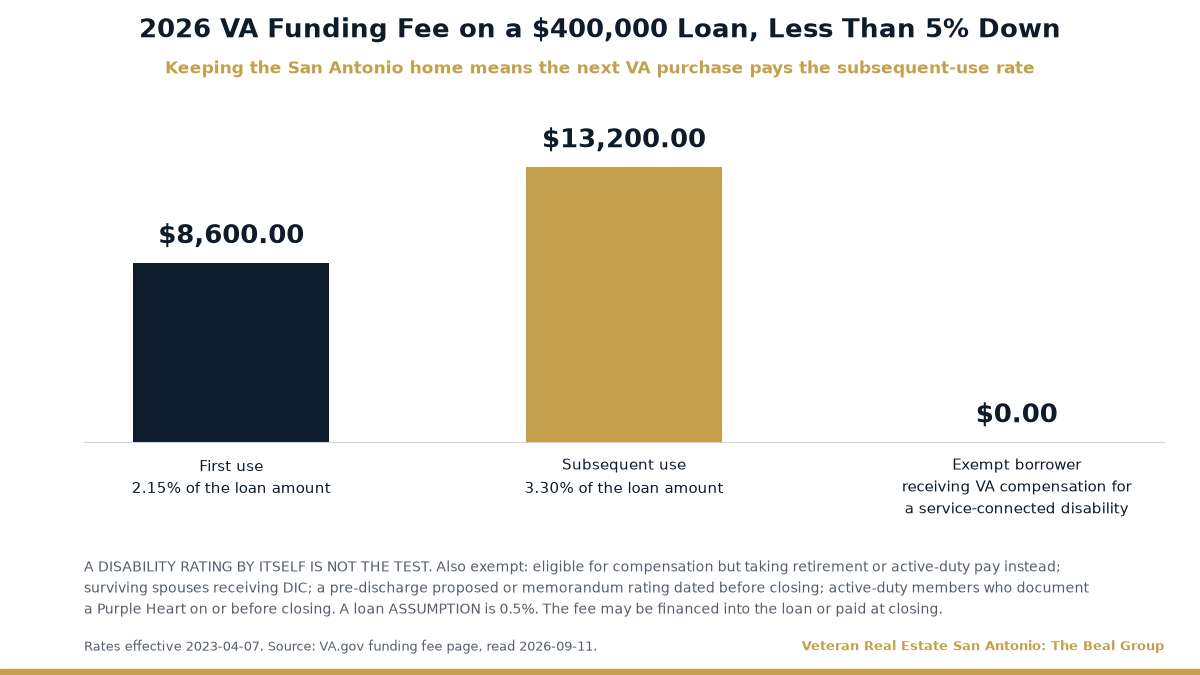
- The second-use VA funding fee is 3.30% with less than 5% down versus 2.15% first use - a $4,600 difference on a $400,000 loan. The fee is waived if you are receiving VA compensation for a service-connected disability, or are eligible to receive it but take retirement or active-duty pay instead. A rating on its own is not the test. A loan assumption carries its own 0.5% fee.
- $208,187 is 25 percent of an $832,750 one-unit limit. That is the ceiling for a remaining-bonus-entitlement calculation, not a cap on a veteran with full entitlement, and the limit that counts is the one in the county you are buying in.
- A retained sub-4 percent VA note has real value against a 6.66 percent 30-year average (week of July 30, 2026). Whether keeping or assuming beats selling depends on your equity, your carrying cost and your timeline, so price all three paths rather than assuming one wins.
In This Guide
- What happens to your VA entitlement when you PCS out of San Antonio?
- How does VA entitlement math actually work in 2026?
- Can I keep my San Antonio home as a rental and buy again at my next base?
- Should I let a buyer assume my low-rate VA loan when I PCS?
- When does selling and restoring entitlement beat keeping the house?
- Which path fits your PCS situation? The decision tree
- How I run this decision with families leaving Lackland, Randolph, and Fort Sam
- FAQ: VA entitlement, assumptions, and PCS from San Antonio
- How do you calculate second-tier entitlement in Bexar County in 2026?
- What do August 2026 rates and Bexar prices do to the math?
What Happens to Your VA Entitlement When You PCS Out of San Antonio?
PCS orders do not cancel, pause, or reset your VA loan benefit. When a family at JBSA-Lackland, JBSA-Randolph, or Fort Sam Houston gets orders to Fort Cavazos, Fort Liberty, or overseas, their VA entitlement simply splits into two buckets: the portion charged to the San Antonio home, and the portion still available. The entire keep-versus-assume-versus-sell decision comes down to how much sits in that second bucket and what it buys at the next base.
Plenty of blogs list the questions military buyers should ask about entitlement. As the agent who actually runs these numbers for JBSA families, I would rather hand you the answers. This guide - part of my PCS from JBSA resource hub - walks the 2026 math path by path, using verified VA and FHFA figures and current SABOR market data, then puts it all into one decision tree.
How Does VA Entitlement Math Actually Work in 2026 (Basic vs Bonus)?
Basic entitlement is $36,000, but that number stopped mattering much years ago. What drives real purchasing power in 2026 is bonus (or "second-tier") entitlement, which scales with the Federal Housing Finance Agency conforming loan limit. The FHFA set the 2026 one-unit baseline at $832,750, up from $806,500 in 2025, and Bexar County and every county surrounding San Antonio sit at that baseline.
The arithmetic is simpler than lenders make it sound. Take 25% of the loan limit where you are buying NEXT. Subtract the entitlement already charged to your San Antonio home, which is 25% of your original VA loan amount. Multiply what is left by four, and that is approximately your maximum zero-down price on VA loan number two.
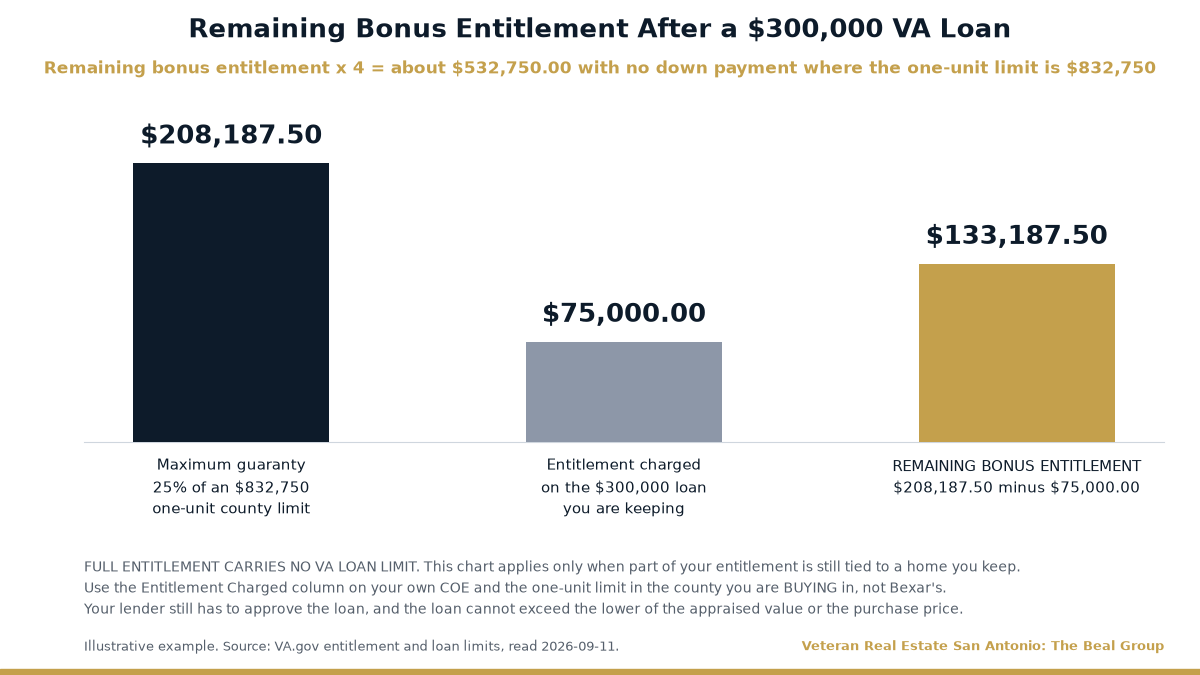
Here is the worked example I show families at my office near JBSA:
| 2026 Entitlement Line Item | Amount | How It Is Calculated |
|---|---|---|
| Maximum guaranty where the one-unit county limit is $832,750 | $208,187.50 | 25% of the one-unit county limit. This is the ceiling for a remaining-bonus calculation, not a cap on full entitlement |
| Entitlement used on $300,000 San Antonio home | $75,000 | Typically 25% of the original loan amount; confirm the exact figure in the Entitlement Charged column of your COE |
| Remaining (second-tier) entitlement | $133,187.50 | $208,187.50 minus $75,000 |
| Max zero-down price at next base (baseline county) | About $532,750 | Remaining entitlement x 4 |
| Max zero-down if next base is a high-cost county | About $949,125 | 25% of $1,249,125 limit minus $75,000, times 4 |
Source: FHFA 2026 conforming loan limit announcement and the VA guaranty formula (25% of county loan limit). Figures assume the loan closed at the stated amount with no prior entitlement use.
Two footnotes matter. First, the limit that counts is the one at your NEXT duty station, so a PCS to a high-cost area like the DC corridor or San Diego actually increases your bonus entitlement. Second, if your remaining entitlement will not cover the full 25% guaranty on the new purchase, you are not blocked - lenders generally look for entitlement, a down payment, or a combination of the two to cover about 25 percent of the loan amount, so a down payment can bridge the gap. For the full buyer-side mechanics of a second use, see my guide to using your VA loan more than once. You can verify your own numbers on your Certificate of Eligibility through VA.gov, and I confirm the COE math with every seller before we pick a path.
Can I Keep My San Antonio Home as a Rental and Buy Again at My Next Base?
Keeping the house is usually the first question a PCS seller asks me, and sometimes the math supports it. Military neighborhoods around San Antonio - Alamo Ranch and Potranco near Lackland, Schertz, Cibolo, and Converse near Randolph, Terrell Heights near Fort Sam Houston - see steady turnover from each inbound PCS cycle. Whether a home carrying a 2.75% to 4% VA loan rents at or above its all-in payment depends on the subdivision, the condition and the month you list it, so get an actual rental analysis instead of assuming BAH covers it.
The trade-offs are specific. Your $75,000 of entitlement stays parked in the rental until you sell or refinance it out, your second purchase pays the subsequent-use funding fee (3.30% with less than 5% down versus 2.15% first use, per the VA funding fee schedule - waived if you are receiving VA compensation for a service-connected disability, or are eligible to receive it but take retirement or active-duty pay instead; separate exemptions cover DIC-receiving surviving spouses, a pre-discharge proposed or memorandum rating dated before closing, and active-duty members who document a Purple Heart on or before closing), and you become a landlord from 1,200 miles away. I walk through the occupancy details in my rent-versus-buy guide for active-duty families, and the rental income itself can help you qualify: lenders commonly credit about 75% of documented market rent against the old payment, though the exact treatment and the documentation required vary by lender.
Planning a PCS to JBSA instead of away from it? Christopher Beal specializes in military relocation - learn more here.
Should I Let a Buyer Assume My Low-Rate VA Loan When I PCS?
This is the entitlement trap I catch most often in seller consultations. Assumptions are having a moment - buyers will pay real money to step into a 2.75% note in a 6%-plus world, and VA loans are assumable by anyone the servicer approves, veteran or not. What the listing agents pushing "assumable!" in their marketing rarely explain is the difference between who CAN assume and what it does to YOUR benefit.
If a civilian assumes your loan, you can walk away with a release of liability, but the $75,000 of entitlement stays pledged to a house you no longer own - potentially for the next 25 years of that loan's life. Your next VA purchase then runs only on what is left. If a qualified veteran assumes and formally substitutes their entitlement for yours, you leave whole. The mechanics, timelines, and servicer quirks are covered step by step in my VA loan assumption guide for PCS sellers, and if you are on the buying side of one, start with how to find and buy an assumable VA loan in San Antonio.
When Does Selling and Restoring My Entitlement Beat Keeping the House?
Selling is the path that hands you back both at once - equity and entitlement. Once the San Antonio loan is paid off at closing, you apply through your lender or VA.gov to restore entitlement, and your next purchase runs on full entitlement again, which carries no VA loan limit; your lender's approval and the appraisal still set the real ceiling. The funding fee does not reset - subsequent use still applies unless you are exempt. VA recognises three restoration routes: you sold the home and paid the loan in full; a qualified Veteran-transferee assumed the loan and substituted their entitlement for the amount you had used; or you repaid the loan in full but kept the home, which VA allows only once. Restoration is a separate request through your lender or VA Form 26-1880.
The timing is where PCS families get squeezed. SABOR reporting through mid-2026 shows San Antonio homes averaging 77 days on market, and SABOR's June 2026 report put that month's median sale price at $329,730 on 3,479 closed sales. A complete pull of all 5,743 Bexar County residential closings between June 13 and September 11, 2026 puts the median at $290,000 (LERA MLS), so read any single-month headline as a snapshot on its own terms rather than as the current market. Add a normal 30 to 45 day escrow and you are realistically 3.5 to 4 months from list to wire - which means listing decisions need to happen when orders are rumored, not when the moving truck is booked. If the truck already left, my remote seller playbook covers selling from the next duty station, and the military capital gains exclusion rules explain why most PCS sellers owe nothing on the gain.
| San Antonio Market Snapshot | June 2026 | What It Means for a PCS Seller |
|---|---|---|
| Median sale price | $329,730 (+4% YoY) | Equity positions from 2020-2022 purchases remain strong |
| Closed sales | 3,479 (+15% YoY) | Buyer activity is real; priced-right homes are moving |
| Average days on market (mid-2026) | 77 | List 4+ months before your report date |
Source: San Antonio Board of REALTORS (SABOR) market reporting, June 2026 release. Days on market is a market-wide average, not a median.
Wondering what your specific home would net after the loan payoff? Request a free home evaluation and I will send the full net sheet.
Which Path Fits Your PCS Situation? The Decision Tree
Run it in this order. Every seller consultation I do at JBSA follows the same four gates. If you want the broader lifestyle and finance version of this decision, my keep, sell, or rent decision framework covers it - this tree is the entitlement-first cut:
- Entitlement gate: Pull the COE. Remaining entitlement x 4 versus home prices at the next base. If it covers what you need, keeping the San Antonio house stays on the table. If not, selling (or veteran-assumption with substitution) moves to the front.
- Cash-flow gate: Market rent x 75% versus PITI. Clears it with margin? Keep-and-rent survives. Misses? The house is a monthly bill at your next base.
- Rate gate: Loan under 4.5%? An assumption listing can command a premium - but only accept the entitlement math if the buyer is a substituting veteran or the premium is large enough to buy out the freeze.
- Life gate: Be honest about managing tenants from Fort Liberty or Ramstein. A great rental with an unwilling landlord becomes a distressed sale in two years - I list several of those every spring.
| Your PCS Situation | Best Pick | Runner-Up | Why |
|---|---|---|---|
| Sub-4% rate, rent covers PITI, strong remaining entitlement | Keep and rent | Veteran assumption | Cash flow plus a second zero-down purchase; the rate is an asset worth holding |
| Need every dollar of equity for the next home | Sell and restore | Sell to a substituting veteran | Full entitlement plus full equity beats any partial path |
| Sub-3.5% rate and buyers competing for assumptions | Veteran assumption with substitution | Civilian assumption at a real premium | Premium price AND released entitlement; civilian version freezes your benefit |
| OCONUS orders, no appetite for tenants | Sell and restore | Keep with professional management | An ocean between you and a rental magnifies every problem |
| Short-notice PCS, home already vacated | Sell remotely | Rent short-term, sell next spring | The remote-seller process is proven; carrying a vacant home rarely pays |
How Do You Calculate Second-Tier Entitlement in Bexar County in 2026?
Second-tier entitlement is arithmetic, not a judgment call. The VA guarantees a percentage of your loan, and lenders size a zero-down loan around the guaranty dollars you still have available. Once you know the two inputs, the ceiling falls out in one line.
The 2026 conforming loan limit for Bexar County is $832,750, up 3.3 percent from $806,500 in 2025. That number does not cap a veteran with full entitlement. It only matters when part of your entitlement is still attached to a house you are not selling, which is the position a PCS family is in whenever they keep the San Antonio house.
The Four-Step Calculation
- Maximum guaranty at that limit. 25 percent of $832,750 equals $208,187. This is the ceiling for the remaining-bonus calculation, not a cap on full entitlement.
- Entitlement already used. Pull the guaranty amount from the Certificate of Eligibility on the loan you are keeping. On most single-family VA loans this is 25 percent of the original loan amount.
- Remaining guaranty. Subtract step two from step one.
- Zero-down ceiling. Multiply the remaining guaranty by four.
Here is the same math on a real San Antonio pattern. A staff sergeant bought in Converse in 2022 for $265,000 with a VA loan, took orders to JBSA-Randolph three years later, and wants to keep the Converse house as a rental.
| Step | Input | Amount |
|---|---|---|
| Maximum guaranty | 25 percent of $832,750 (2026 Bexar limit) | $208,187 |
| Entitlement in use | 25 percent of the $265,000 Converse loan | $66,250 |
| Remaining guaranty | $208,187 minus $66,250 | $141,937 |
| Zero-down ceiling on loan two | $141,937 times four | $567,750 |
| Bexar median sale price | 30 days ending August 1, 2026 | $304,950 |
Source: 2026 FHFA conforming loan limit for Bexar County; SABOR and LERA MLS closed sales, Bexar County, thirty days ending August 1, 2026. Entitlement figures are illustrative and follow the standard 25 percent guaranty pattern. Your Certificate of Eligibility governs.
Where the ceiling bites is specific to you: it is your remaining bonus entitlement times four, which in the worked example above is $532,750.00. Buying in Alamo Heights, Stone Oak, or the Dominion on a second-tier loan is where the shortfall shows up, and the fix is a down payment equal to 25 percent of the amount above the ceiling, not a bigger entitlement. If you need every dollar of entitlement back, VA recognises three routes: sell the first home and pay that loan in full; have a qualified Veteran-transferee assume the loan and substitute their entitlement for the amount you used; or repay the loan in full while keeping the home, which VA allows only once. I walk through what restoration requires in the entitlement restoration section of my VA loan and divorce guide, and the down payment mechanics live in my San Antonio VA loan down payment guide.
What Do August 2026 Rates and Bexar Prices Do to the Keep, Assume, or Sell Math?
The spread between your old rate and today's rate is the whole ballgame. Every one of these three options is really a question about what that below-market note is worth to you, to a renter, or to a buyer.
| Number | August 2026 reading | Why it moves your decision |
|---|---|---|
| 30-year fixed average | 6.66 percent (week of July 30, 2026; 6.58 percent the prior week, 6.72 percent a year earlier) | Sets the payment on the home you buy at the new duty station and the payment your buyer would face without an assumption. |
| 15-year fixed average | 6.04 percent | Matters if you are paying down the retained property to improve rental cash flow. |
| Bexar median sale price | $304,950 | Median for the 30 days ending August 1, 2026. Anchors what a sale actually nets and how much equity is available for the next down payment. |
| Average days on market | 79 days | A sale is not a fast lever. Back it into your report date or plan to carry the house. |
| Sale-to-list ratio | 97.7 percent | Expect a real negotiation. Sellers are conceding, which also means your buyer-side leverage at the new base is good. |
Sources: Freddie Mac Primary Mortgage Market Survey, week ending July 30, 2026; SABOR and LERA MLS closed and active data, Bexar County, thirty days ending August 1, 2026.
2026 VA Funding Fee Table
The funding fee is the line most second-time users forget to price. With less than 5 percent down it goes from 2.15 percent on a first-use loan to 3.30 percent on a subsequent-use loan. You may finance it into the loan or pay it at closing; financing it raises the balance and the payment on the house you are buying next.
| Down payment | First use | Subsequent use |
|---|---|---|
| Less than 5 percent | 2.15 percent | 3.30 percent |
| 5 percent up to 10 percent | 1.50 percent | 1.50 percent |
| 10 percent or more | 1.25 percent | 1.25 percent |
| Any amount, veteran receiving VA disability compensation | Exempt | Exempt |
Source: U.S. Department of Veterans Affairs funding fee schedule, 2026 purchase loans.
Three practical reads on the August 2026 numbers. If your retained note is below about 4 percent, an assumption is the most valuable thing you own in a negotiation, because your buyer is comparing it to 6.66 percent. If you are selling, price to the 97.7 percent sale-to-list reality and start early enough to absorb 79 days plus closing, which is the timeline I lay out in my PCS report-date timeline guide. If you are buying at the new base, the same slow market that hurts you as a seller helps you as a buyer, and the current leverage picture is in my buyer or seller market breakdown. Either way, expect the appraiser to hold the line on minimum property requirements, which I cover in my VA appraisal requirements guide.
My Serve and Save program credits 1 percent of my gross buyer-agent commission toward your closing costs for every verified year of active service. It is a closing-cost credit, so it needs your lender's approval and it has to appear on the Closing Disclosure. It is not a percentage of the purchase price, and it is not a cash payment to you. Ask me to price it against your actual funding fee rather than assuming it covers one.
How Do I Run This Decision With Families Leaving Lackland, Randolph, and Fort Sam Houston?
The process is deliberately boring, because a PCS is chaotic enough. I pull your COE and confirm exactly how much entitlement is charged and what remains - the number on the certificate, not a calculator estimate. We price the home against current SABOR comps, build the net sheet, and run the 75% rent credit against your PITI using real leases from your subdivision, whether that is Alamo Ranch, Schertz, Stone Oak, or out toward Boerne.
Then we pressure-test the assumption angle if your rate justifies it, including what a substitution-of-entitlement buyer looks like and how long that search realistically takes in the current market. If the next move includes a purchase, Serve & Save credits 1 percent of my gross buyer-agent commission toward your closing costs for each verified year of active service, subject to lender approval and shown on the Closing Disclosure. If the decision lands on selling after you have already reported to the next base, the entire transaction runs remotely; I close for JBSA families from Germany, Korea, and both coasts every year.
About the Author: Christopher Beal
Christopher Beal is a U.S. Army veteran and the Owner of Veteran Real Estate San Antonio, a Beal Group practice brokered by eXp Realty (TREC License #723559). A Military Relocation Professional (MRP) and VAREP member, he is a 7-time eXp Realty ICON agent, winner of Best Real Estate Agency in the 2026 Best of San Antonio Readers' Choice (San Antonio Current, 100,000+ voters), and a 3x San Antonio Business Journal Top 25 Individual Agent (#13 in 2024, #14 in 2025, #20 in 2026). His recognition also includes 3x Platinum Top 50, 2x RateMyAgent Agent of the Year, 2x Real Producers Top 100, Five Star Professional (2026), and a RealTrends 2026 ranking. He has helped 325+ families, closed more than $125M in career volume, and holds 5.0 stars across 370+ verified reviews, working almost exclusively with military and veteran buyers and sellers across Bexar, Comal, Kendall, Medina, and Bandera counties, with a focus on VA loans, PCS moves, and homebuying near JBSA-Lackland, JBSA-Randolph, and Fort Sam Houston. Second-tier entitlement questions come across his desk nearly every week of PCS season, and he runs the keep, assume, or sell math with clients before they ever call a lender. He can be reached at (210) 882-8583.
Explore More Resources
- VA Home Loans
- Military Relocation
- Free Home Evaluation
- Serve & Save
- Client Reviews
- About Christopher
FAQ: VA Entitlement, Assumptions, and PCS From San Antonio
Can I have two VA loans at the same time?
Yes. If you have remaining second-tier entitlement after your San Antonio purchase, you can carry a VA loan here and open a second VA loan at your next duty station, often with zero down. The limit is the math, not a rule against two loans.
How much entitlement do I get back when I sell my San Antonio home?
All of it. Once the VA loan is paid off at closing and you apply for restoration, your entitlement is restored in full, and full entitlement carries no VA loan limit. Your lender's approval and the appraisal still set the actual loan amount.
What happens to my VA entitlement if a civilian assumes my loan?
It stays tied to the assumed loan until that loan is completely paid off, which can be decades. A release of liability protects your credit, but it does not release your entitlement.
Can another veteran assume my VA loan and free up my entitlement?
Yes. An eligible veteran buyer can formally substitute their entitlement for yours during the assumption. That is the only assumption structure that leaves your benefit fully intact.
What is the VA funding fee for a second VA loan in 2026?
3.30% of the loan amount for subsequent use with less than 5% down, versus 2.15% for first use. It drops to 1.50% with 5% down and 1.25% with 10% down, and a loan assumption carries 0.5% instead. The fee is waived if you are receiving VA compensation for a service-connected disability, or are eligible to receive it but take retirement or active-duty pay instead; DIC-receiving surviving spouses, service members holding a pre-discharge proposed or memorandum rating dated before closing, and active-duty members who document a Purple Heart on or before closing are also exempt.
What is the 2026 VA loan limit in San Antonio?
Bexar County follows the 2026 baseline conforming limit of $832,750. With full entitlement there is no cap on loan size - the limit only matters when you have partial entitlement tied up in another home.
Do I have to sell my home to restore my VA entitlement?
Not always. VA recognises three routes: you sell the home and pay the loan in full; a qualified Veteran-transferee assumes the loan and substitutes their entitlement for the amount you used; or you repay the loan in full but keep the home, which VA allows only once. Restoration is a separate request, filed through your lender or on VA Form 26-1880.
Does renting out my San Antonio home violate VA occupancy rules?
No. The occupancy requirement applies when you buy - you certify you intend to live in the home. After you have occupied it, converting it to a rental because of PCS orders is a well-established and legitimate use.
How long does it take to sell a San Antonio home in 2026?
SABOR data through mid-2026 shows an average of 77 days on market, plus a typical 30 to 45 day closing. PCS sellers should plan on 3.5 to 4 months from listing to funded sale.
How much second VA loan can I get in San Antonio if I keep my current house?
Start with 25 percent of the one-unit limit in the county you are buying in, which is $208,187 where that limit is $832,750. Subtract the Entitlement Charged shown on your COE for the loan you are keeping, then multiply the remainder by four. If $66,250 is charged, that is roughly $567,750 of zero-down room, against a $290,000 median closed sale price across all 5,743 Bexar County residential closings between June 13 and September 11, 2026 (LERA MLS). Lender approval and the appraisal still apply.
Does the VA funding fee go up on a second VA loan?
Yes. With no money down, the fee is 2.15 percent on a first-use loan and 3.30 percent on a subsequent-use loan, a $3,450 difference on a $300,000 purchase. Putting 5 percent down drops both to 1.50 percent, and 10 percent down drops both to 1.25 percent. Any veteran receiving VA disability compensation is exempt entirely.
Ready to run your numbers before orders drop? Three ways to start:
Call or text Christopher Beal at (210) 882-8583 for a same-day entitlement and net-sheet review.
Email [email protected] with your loan balance and PCS timeline for a written keep-assume-sell comparison.
Request a free home evaluation at veteranrealestatesa.com/home-evaluation to see exactly what your San Antonio home nets in today's market.
Watch: Two VA Loans at Once, Explained
You can carry two VA loans at the same time. Whether you should comes down to entitlement math. Here is the fast version before your next set of orders.
Watch: Restoring Your VA Entitlement After You Sell
Selling the house does not restore your entitlement by itself -- that is a separate filing. Here is what a PCS seller submits, and how one-time restoration fits with second-tier entitlement.
Watch: Letting a Buyer Assume Your VA Loan
The assumption question is really two questions: who is assuming, and whether you are actually off the note when it closes. This one walks a JBSA seller through both, with the same numbers I run on a net sheet.
The short version: an eligible veteran buyer who substitutes their own entitlement gets yours restored, while a civilian assumer leaves your entitlement parked on that loan until it is paid in full. Approval is also what releases you from the debt - a handshake takeover leaves you liable and can trigger the due-on-sale clause. A servicer with automatic authority has 45 calendar days to decide a complete assumption application and another 45 days after closing to send the package to VA.
Two Questions This Video Answers
Am I still liable after a buyer assumes my VA loan?
Only an approved assumption releases you. When a creditworthy buyer formally takes on your obligation to the lender and to VA, you are released from liability - that is what VA Form 26-6381 is for. If someone simply takes over the payments without approval, you stay on the note and the holder can call the loan due and payable (VA Form 26-8978).
What does a VA loan assumption actually cost in Texas in 2026?
Most of it lands on the buyer, and it is more than the headline processing fee. VA allows a 0.5 percent funding fee on the loan balance, paid in cash at closing rather than financed, unless the assumer is exempt. The servicer may also charge a processing fee capped at $300 where it has automatic authority ($250 on VA prior-approval cases), a credit report fee, and the VA Assumption Locality Variance - $404 in the South region, which includes Texas, on assumptions closed after February 26, 2024. The $300 limit caps that base processing fee, not the total. Recording and title costs still apply, and the number that usually decides the deal is the equity gap: your buyer has to cover the difference between the price and the loan balance in cash or with a second lien. Confirm current amounts with the servicer before you price a deal around them.
Want this run against your actual balance and payoff? Ask me for a net sheet both ways, assumption and conventional sale, before your orders drop.
Sources: VA Circular 26-24-5 and its Exhibit A locality variance table (February 26, 2024), VA Circular 26-23-10, and the VA funding fee and closing costs page. Checked September 17, 2026.
Categories
- All Blogs (357)
- Alamo Heights (4)
- awards (4)
- Best Neighborhoods in San Antonio (13)
- Buyer (16)
- Buyer Education (87)
- Community Events (4)
- Hill Country (17)
- JBSA (46)
- Local Guide (6)
- Luxury (28)
- Luxury Real Estate (26)
- Market Trends (19)
- Market Update (14)
- Military Relocation (114)
- Military Retirement (3)
- Mortgage (19)
- Neighborhood Guides (19)
- neighborhoods (5)
- New Construction (16)
- PCS (42)
- Real Estate (40)
- reviews (3)
- San Antonio (53)
- San Antonio Lifestyle (4)
- San Antonio Market (5)
- San Antonio Neighborhoods (45)
- San Antonio Real Estate (100)
- San Antonio, Veterans Resources, VA Loans (5)
- Seller (55)
- VA Home Loans (30)
- VA Loans (35)
- Va Loans & Financing (27)
- Veterans (10)
- Veterans Resources (40)
Recent Posts