VA Loan Benefits and Assistance Programs for Veterans in 2026
LAST UPDATED: SEPTEMBER 1, 2026 | BY CHRISTOPHER BEAL, U.S. ARMY VETERAN & REALTOR
A VA loan in 2026 still lets a qualified San Antonio veteran buy a primary residence with zero down payment, no monthly mortgage insurance, and a capped set of closing costs. That is the headline benefit, and it has not changed. What has changed is everything stacked around it: the Texas Veterans Land Board rate advantage, the property tax exemption tiers at the Bexar Appraisal District, the down payment assistance available through TSAHC and the City of San Antonio, and the VA policy on who pays your agent.
I am Christopher Beal, a U.S. Army veteran and the Owner of Veteran Real Estate San Antonio, and almost every purchase I close runs on VA financing somewhere in Bexar, Comal, Kendall, Medina, or Bandera County. This guide is the 2026 version of what I walk clients through at the kitchen table.
KEY TAKEAWAYS
- Full entitlement means no VA loan limit. Bexar County caps only apply if you have a VA loan already in use or a prior default.
- The 2026 funding fee is 2.15 percent of the loan on a first no-down purchase and 3.3 percent on a subsequent use. Veterans receiving service connected disability compensation pay zero.
- A 100 percent service connected disability rating removes the entire residence homestead property tax bill in Texas. That is often worth more per month than a half point of interest rate.
- Texas Veterans Land Board, TSAHC Homes for Texas Heroes, and the City of San Antonio Homeownership Incentive Program all stack on top of a VA loan.
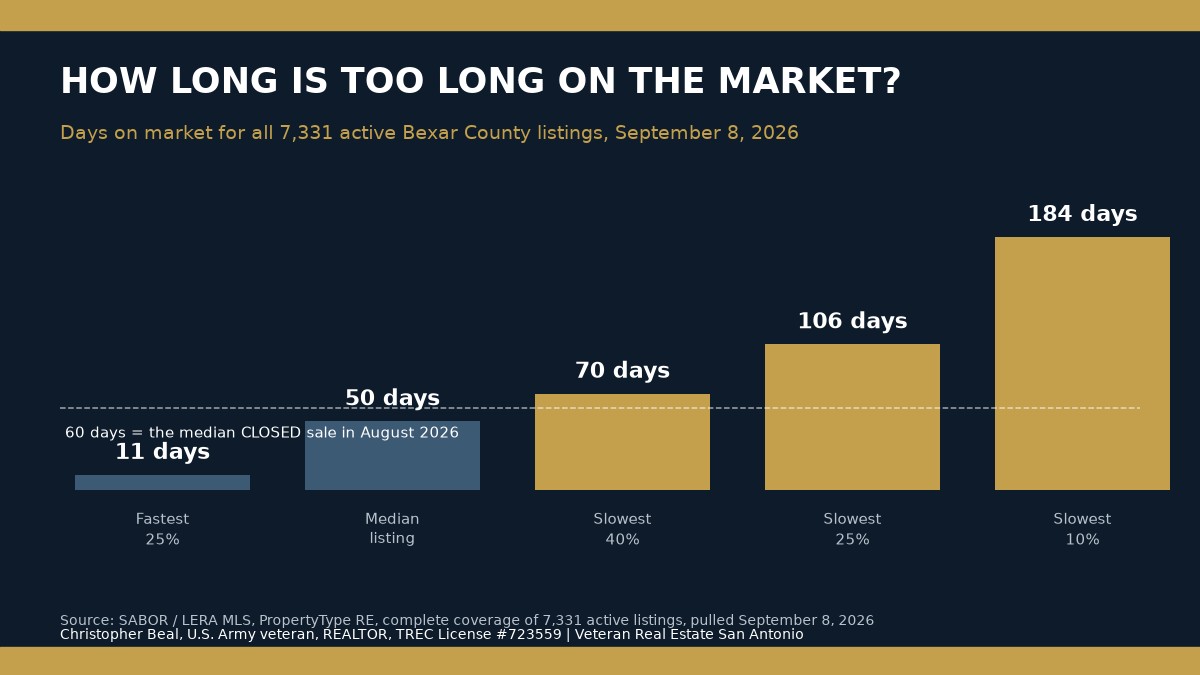
- Bexar County sold homes ran a $280,000 median with 75 days on market between June 3 and September 1, 2026. That is a market where a VA buyer can negotiate, not one where VA offers get thrown out.
What a VA Loan Actually Gets You in 2026
The VA does not lend you money. It guarantees a portion of a loan made by a private lender, and that guarantee is what buys you the terms. Understanding that one sentence explains why every benefit below exists.
The core benefits for a San Antonio buyer in 2026 are these. Zero down payment on a primary residence, subject to lender approval and the property appraising. No monthly private mortgage insurance, which on a $300,000 conventional loan with 5 percent down would typically run somewhere between $90 and $200 per month for years. Interest rates that in most weeks price below comparable conventional rates. A limit on which closing costs you are allowed to pay, including a hard prohibition on paying a lender origination fee above one percent of the loan.
Add to that the assumability feature, which almost nobody talks about until it matters. A VA loan can be assumed by a qualified buyer, veteran or civilian, at the original interest rate. If you close in 2026 at a rate in the sixes and rates move higher, that assumable loan becomes a marketing asset when you sell on your next set of orders. I cover the mechanics in detail in my guide to VA loan assumption in San Antonio.
The 2026 VA Loan Numbers San Antonio Veterans Need
If you have full entitlement, there is no VA loan limit, and there has not been one since the Blue Water Navy Vietnam Veterans Act took effect in 2020. You can buy at $250,000 or at $900,000 with zero down, provided a lender will approve you at that payment and the home appraises.
The county limit only becomes relevant when your entitlement is partial. That happens when you already have an active VA loan on another property, most often a home you kept back at a prior duty station, or when you had a prior VA loan foreclose. In that case Bexar County follows the Federal Housing Finance Agency conforming loan limit, which is reset every January, and your remaining entitlement determines how much you can borrow without a down payment.
Here is how the three loan types compare for a San Antonio buyer this year.
| Feature | VA Loan | FHA Loan | Conventional |
|---|---|---|---|
| Minimum down | 0 percent | 3.5 percent | 3 to 5 percent |
| Monthly mortgage insurance | None | Yes, usually for the life of the loan | Yes until 20 percent equity |
| Upfront fee | Funding fee, waived for disability compensation recipients | 1.75 percent upfront MIP, never waived | None |
| Assumable | Yes, by qualified buyers | Yes, by qualified buyers | Almost never |
| Property condition standards | VA Minimum Property Requirements | HUD minimum standards | Lender and appraiser discretion |
| Occupancy | Primary residence only | Primary residence only | Any occupancy type |
If you want the longer version of that comparison, I broke it down at length in VA loan versus conventional loan for San Antonio military buyers and in VA loan versus FHA loan in San Antonio.
The 2026 VA Funding Fee, and How to Legally Avoid It
The funding fee is the only meaningful cost that is unique to a VA loan, and a large share of San Antonio veterans do not pay it at all. Anyone receiving VA compensation for a service connected disability is exempt, as are surviving spouses receiving Dependency and Indemnity Compensation and Purple Heart recipients on active duty.
| Down payment | First use | Subsequent use |
|---|---|---|
| Less than 5 percent | 2.15 percent | 3.3 percent |
| 5 to 9.99 percent | 1.5 percent | 1.5 percent |
| 10 percent or more | 1.25 percent | 1.25 percent |
On a $300,000 purchase with nothing down and no exemption, that is $6,450 on a first use. The fee can be financed into the loan rather than paid in cash, which is what most of my buyers do. If your disability rating comes through after closing, you can apply to the VA for a refund of the fee you already paid, and I have had clients recover the full amount months later.
Texas and San Antonio Programs That Stack On Top
The mistake I see most often is treating the VA loan as the whole benefit package when it is really the foundation layer. Four programs sit on top of it here, and none of them cancel the others out.
Texas Veterans Land Board Housing Assistance Program
The Texas Veterans Land Board, administered under the Texas General Land Office, offers a home loan program for Texas veterans that often prices below the open market rate, with an additional rate discount for veterans with a disability rating of 30 percent or higher. It is used together with VA financing through a participating lender. You can review current rates and eligibility at the Texas Veterans Land Board.
Texas Disabled Veteran Property Tax Exemptions
This is the single most undervalued benefit in the state, and it is administered locally by the Bexar Appraisal District. A veteran with a 100 percent service connected disability rating, or one rated individually unemployable, receives a total exemption from property tax on the residence homestead. Partial ratings receive fixed exemption amounts on the appraised value, tiered from the 10 to 29 percent band up through the 70 to 100 percent band.
Run the arithmetic on that. Property tax on a $320,000 San Antonio home commonly lands somewhere near $650 to $750 per month inside the escrow payment. A total exemption removes that line entirely, which changes what house you can afford far more than shopping a lender for an eighth of a point. Details are published by the Texas Comptroller of Public Accounts, and the application is filed with the county appraisal district.
TSAHC Homes for Texas Heroes
The Texas State Affordable Housing Corporation runs a program for veterans and other qualifying professions that provides down payment and closing cost assistance, structured either as a grant or as a deferred second lien. Because a VA buyer usually is not bringing a down payment, this assistance most often gets applied to closing costs and prepaid escrows instead.
City of San Antonio Homeownership Incentive Program
The City of San Antonio Neighborhood and Housing Services Department runs the Homeownership Incentive Program, which provides assistance to income qualified buyers purchasing inside city limits. Funding tiers and maximum amounts are reset with each funding cycle, so confirm the current numbers with the city before you write an offer around them.
The veterans who get the most out of these programs are not the ones who found a better interest rate. They are the ones who filed the property tax exemption, stacked closing cost assistance, and kept their entitlement clean for the next duty station.
CHRISTOPHER BEAL, OWNER, VETERAN REAL ESTATE SAN ANTONIO
My own Serve and Save program sits alongside these. It reduces closing costs for veterans, active duty service members, and first responders who buy or sell with me, and it is applied at the closing table rather than paid out separately.
What Changed for VA Buyers Between 2025 and 2026
Two changes matter more than anything else on the policy side, and both concern who pays for representation.
Since August 2024 the VA has permitted veteran buyers to pay their own agent's compensation when the amount is reasonable and customary for the market. Before that policy shift, a VA buyer whose seller declined to contribute toward buyer agent compensation was in a genuinely awkward spot. Today it is a negotiable line like any other, and in Bexar County sellers still frequently contribute.
The second change is market condition rather than policy. Bexar County recorded a $280,000 median sale price with an average of 75 days on market and a 98.8 percent list to sale price ratio in the June 3 through September 1, 2026 window, based on a 1,000 sale SABOR MLS sample. Average sold price per square foot was $158.62. Active inventory carried a $278,700 median list price. Those are not the numbers of a market that rejects VA offers. They are the numbers of a market where a well prepared VA buyer can ask for a rate buydown and closing cost help and actually get it.
For a deeper read on how that market shift affects timing, see whether San Antonio is a buyer or seller market in 2026.
Common VA Loan Myths, Corrected
Most of the resistance a VA offer meets in San Antonio comes from listing agents repeating things that stopped being true years ago.
The myth that VA loans take longer to close is the most persistent one. In practice my VA files close on the same 30 to 35 day timeline as conventional files, and the difference between a fast close and a slow one is the lender, not the loan type.
The myth that VA appraisals kill deals is closer to reality but still overstated. The VA appraiser is checking Minimum Property Requirements, which focus on safety, soundness, and sanitation. Peeling paint on a pre 1978 home, an inoperable HVAC system, an active roof leak, or missing handrails will get flagged. Cosmetic condition will not. I wrote about exactly what gets called out in my guide to VA appraisal requirements in San Antonio.
The myth that you only get to use it once is simply wrong. Entitlement restores when you sell and pay off the loan, and in the right circumstances you can carry two VA loans at the same time using remaining entitlement. That is how a career service member ends up owning at two duty stations.
How I Run a VA Purchase in San Antonio
The order of operations matters more than any single benefit, because a program you find out about after you are under contract is usually a program you cannot use.
First, get your Certificate of Eligibility and a real underwritten pre approval, not a rate quote. Second, file or confirm your property tax exemption status so we can budget the actual monthly payment rather than a generic escrow estimate. Third, identify which assistance programs you qualify for before we write, because several of them require the lender to register the file up front. Fourth, we shop, and I structure the offer around seller contributions toward your closing costs rather than chasing a lower purchase price that does not move your payment much.
My full walkthrough of step one is at the VA loan pre approval process in San Antonio, and if you are still working out your cash to close, start with what a VA loan actually requires as a down payment.
About the Author
Christopher Beal is a U.S. Army veteran and the Owner of Veteran Real Estate San Antonio, a Beal Group practice brokered by eXp Realty (TREC License #723559). A Military Relocation Professional (MRP) and VAREP member, he is a 7-time eXp Realty ICON agent, winner of Best Real Estate Agency in the 2026 Best of San Antonio Readers' Choice (San Antonio Current, 100,000+ voters), and a 3x San Antonio Business Journal Top 25 Individual Agent (#13 in 2024, #14 in 2025, #20 in 2026). His recognition also includes 3x Platinum Top 50, 2x RateMyAgent Agent of the Year, 2x Real Producers Top 100, Five Star Professional (2026), and a RealTrends 2026 ranking. He has helped 325+ families, closed more than $125M in career volume, and holds 5.0 stars across 370+ verified reviews, working almost exclusively with military and veteran buyers and sellers across Bexar, Comal, Kendall, Medina, and Bandera counties, with a focus on VA loans, PCS moves, and homebuying near JBSA-Lackland, JBSA-Randolph, and Fort Sam Houston. He has walked hundreds of San Antonio veterans through the exact benefit stack described above. He can be reached at (210) 882-8583.
Frequently Asked Questions
Is there a VA loan limit in San Antonio in 2026?
Not if you have full entitlement. The VA loan limit was eliminated for full entitlement borrowers effective in 2020. Bexar County limits only apply when your entitlement is partial, meaning you have another active VA loan or a prior VA foreclosure, and in that case the county figure follows the FHFA conforming loan limit reset each January.
How much is the VA funding fee in 2026?
On a purchase with no down payment it is 2.15 percent of the loan amount on a first use and 3.3 percent on a subsequent use. It drops to 1.5 percent with 5 to 9.99 percent down and 1.25 percent with 10 percent or more down. Veterans receiving service connected disability compensation pay nothing.
Do I still pay property taxes in Texas with a 100 percent disability rating?
Not on your residence homestead. A 100 percent service connected disability rating, or an individual unemployability determination, qualifies you for a total exemption from property tax on your primary residence. You file the application with the Bexar Appraisal District, and partial ratings receive tiered fixed exemption amounts instead.
Can I use a VA loan and down payment assistance at the same time?
Yes. TSAHC Homes for Texas Heroes assistance, Texas Veterans Land Board financing, and the City of San Antonio Homeownership Incentive Program can all be layered with VA financing. Because most VA buyers are putting nothing down, the assistance typically goes toward closing costs and prepaid escrows rather than a down payment.
Do sellers in San Antonio still refuse VA offers?
Some listing agents still push back, but far less than they did. With Bexar County averaging 75 days on market and a 98.8 percent list to sale ratio in mid 2026, sellers are considering strong offers regardless of loan type. A clean pre approval and a well written offer solve most of the objection.
How many times can I use my VA loan benefit?
There is no lifetime cap. Your entitlement restores each time you sell the home and pay off the VA loan. You can also hold two VA loans simultaneously using remaining entitlement, which is common for service members who buy at successive duty stations.
What will a VA appraiser make the seller repair?
Items that violate Minimum Property Requirements, which cover safety, soundness, and sanitation. Typical call outs are chipping paint on homes built before 1978, roof leaks, non functioning HVAC, exposed wiring, missing handrails, and active wood destroying insect damage. Cosmetic issues are not repair requirements.
Can I pay my own agent with a VA loan in 2026?
Yes. Since August 2024 the VA has allowed veteran buyers to pay buyer agent compensation when it is reasonable and customary for the market. In practice, San Antonio sellers still contribute in a large share of transactions, so it remains a negotiable term.
Can I get a refund of the funding fee if my disability rating comes through later?
Yes, if the effective date of your disability compensation award is on or before the closing date of the loan. You apply through the VA and your lender, and refunds are commonly processed months after closing.
Talk to Someone Who Has Used the Benefit
If you are buying near JBSA-Lackland, JBSA-Randolph, or Fort Sam Houston, or anywhere across Bexar, Comal, Kendall, Medina, and Bandera counties, I will map your specific entitlement, exemption status, and eligible assistance programs before you look at a single house. Call or text me at (210) 882-8583, or start with my VA loan specialist guide for San Antonio.
Categories
- All Blogs (354)
- Alamo Heights (4)
- awards (4)
- Best Neighborhoods in San Antonio (13)
- Buyer (16)
- Buyer Education (86)
- Community Events (4)
- Hill Country (17)
- JBSA (43)
- Local Guide (6)
- Luxury (28)
- Luxury Real Estate (26)
- Market Trends (19)
- Market Update (14)
- Military Relocation (111)
- Military Retirement (3)
- Mortgage (19)
- Neighborhood Guides (18)
- neighborhoods (5)
- New Construction (16)
- PCS (42)
- Real Estate (40)
- reviews (3)
- San Antonio (53)
- San Antonio Lifestyle (4)
- San Antonio Market (5)
- San Antonio Neighborhoods (43)
- San Antonio Real Estate (100)
- San Antonio, Veterans Resources, VA Loans (5)
- Seller (55)
- VA Home Loans (30)
- VA Loans (35)
- Va Loans & Financing (27)
- Veterans (10)
- Veterans Resources (40)
Recent Posts