VA Loan Specialist in San Antonio: What Every Veteran Home Buyer Needs to Know in 2026
LAST UPDATED: SEPTEMBER 12, 2026 | BY CHRISTOPHER BEAL, U.S. ARMY VETERAN & REALTOR
A VA-experienced San Antonio Realtor coordinates your home search and contract. A licensed lender determines loan eligibility, pricing, and approval. Christopher Beal, Army veteran and REALTOR with eXp Realty (TREC #723559), serves buyers and sellers across Bexar, Comal, Kendall, Medina, and Bandera counties.
VA Loan Specialist in San Antonio: What Every Veteran Home Buyer Needs to Know in 2026
Buying with VA financing calls for clear coordination among the buyer, lender, real estate agent, title company, and other transaction professionals. This guide explains how to compare representatives, plan a JBSA relocation, evaluate property condition, and discuss closing costs before signing a purchase contract.
(210) 882-8583 | [email protected]
Why Do You Need a VA-Savvy Realtor - Not Just a VA Lender?
Most veterans understand they need a lender who handles VA loans. What many do not realize is that the Realtor you choose matters just as much as the lender when you are using a VA loan. Here is why:
Offer preparation. Your agent coordinates the proposed price, deadlines, inspections, and seller-paid cost request with your financing plan. Seller acceptance remains a negotiation.
Property condition. A VA appraisal evaluates value and Minimum Property Requirements. It does not replace an independent home inspection. Discuss potential condition issues with the lender and inspector early.
Closing costs. VA limits seller concessions to 4% of the home's reasonable value. Ordinary loan closing-cost credits are treated separately. Have your lender classify proposed credits before you rely on an estimate. VA closing-cost guidance.
What Are the 2026 VA Loan Limits and Rates for San Antonio?
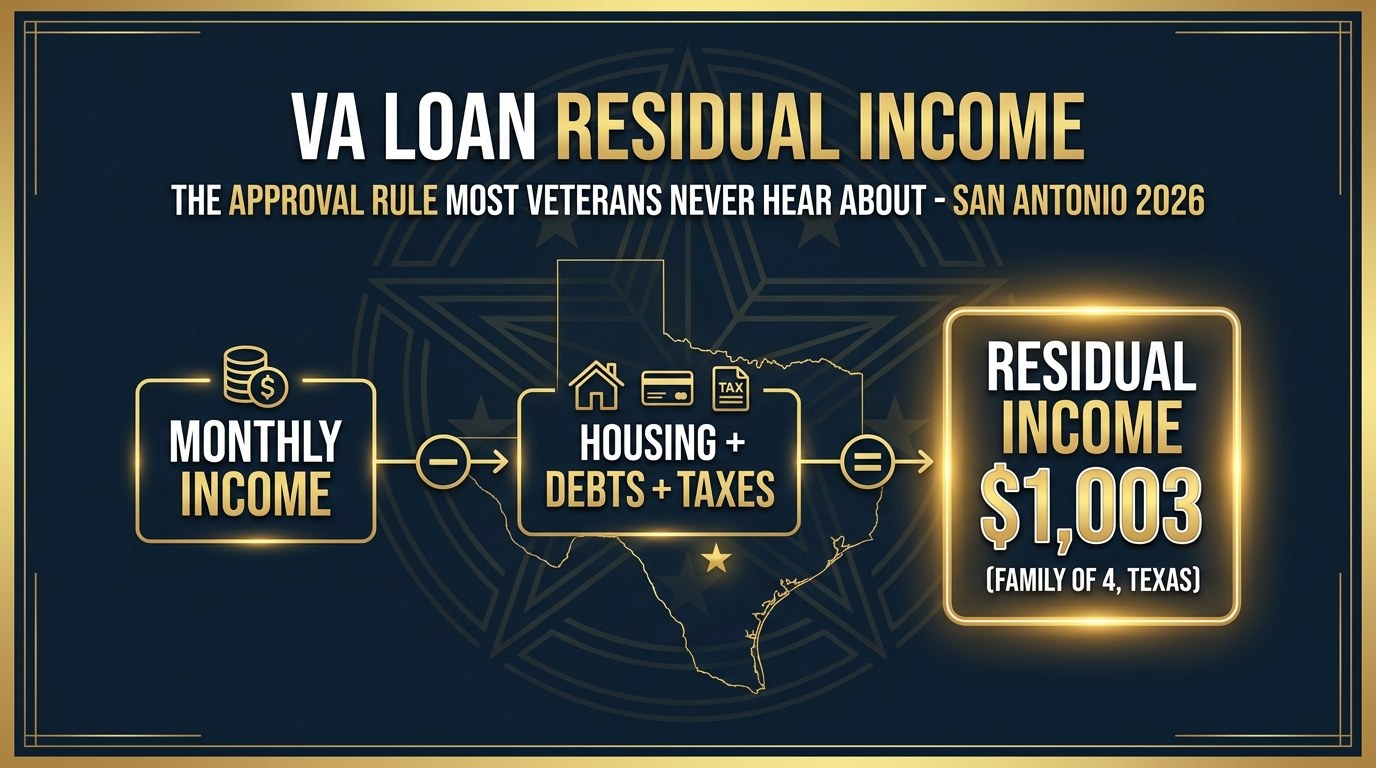
With full entitlement, VA does not impose a county loan limit. The lender must still approve the loan and the appraisal must support the purchase. If entitlement is already in use, ask the lender to calculate remaining entitlement and any down payment. VA entitlement guidance.
Request current written Loan Estimates for the same purchase price, loan amount, lock period, and closing date. Rates, points, lender credits, and fees vary. A VA loan should be compared with available alternatives using total cost and your expected ownership period.
For a nonexempt purchase with less than 5% down, VA lists a funding fee of 2.15% for first use and 3.3% for subsequent use. Other down payments have different rates. Exemptions include qualifying disability-compensation recipients and certain other borrowers; the Purple Heart provision applies to qualifying active-duty service members. Ask the lender to verify your exemption and consult the VA fee schedule.
What Should You Look for in a VA Loan Lender in San Antonio?
Your lender handles the money. Your Realtor handles the strategy. Both need to be sharp for a VA transaction to close smoothly. Here is what separates a qualified VA lender from one that will slow you down:
Relevant VA experience. Ask how the lender coordinates the COE, appraisal, Minimum Property Requirements, underwriting, and closing schedule. Ask who will communicate updates and resolve document questions.
Transparent pricing. Compare written estimates with the same assumptions, including points, credits, cash to close, and total monthly payment. A headline rate alone does not establish which loan is less expensive.
Clear, strong pre-approval letters. In a competitive market, a vague pre-qualification letter will not get your offer accepted. Your lender should provide a pre-approval that includes verified income, credit review, and clear loan amount - giving listing agents confidence that your VA financing will close.
Direct communication with your Realtor. The best VA transactions happen when your lender and Realtor are communicating directly throughout the process. Delays in document requests, appraisal orders, or underwriting conditions can kill a deal. A lender who goes dark for days at a time is a liability.
Consistent on-time closing record. Ask your lender about recent closing timelines, common delays, and the documents needed for your proposed closing date.
What Makes a Realtor Truly Qualified as a VA Loan Specialist?
Claiming to be "military-friendly" is easy. Proving it requires documented experience and specific expertise. Here is what to demand from any San Antonio Realtor who says they specialize in VA loans:
Genuine VA transaction volume. How many VA-financed deals has this agent closed in the past 12 months? In the past 5 years? There is no substitute for repetition when it comes to navigating VA-specific challenges like MPR issues, tidewater appraisals, and entitlement restoration.
Understanding of VA appraisal MPRs. Your Realtor should be able to walk through a property before you make an offer and identify potential MPR issues - peeling paint on pre-1978 homes, missing handrails, non-functional utilities, pest damage, roof condition. If they cannot do this, they are not a VA specialist.
JBSA and PCS timeline familiarity. Military relocations run on strict timelines. Your Realtor should understand PCS orders, BAH budgeting, report dates, and the compressed schedule most military families operate under. A PCS-experienced agent builds your home search timeline around your report date - not the other way around.
Network of trusted service providers. Ask about inspectors, title companies, insurance agents, and contractors experienced with the property type. The lender coordinates the VA appraisal through the applicable process; an agent does not select the VA appraiser.
How Should You Plan a VA-Financed Purchase Around JBSA?
Start with your reporting location, lender-approved budget, property requirements, and intended ownership period. JBSA-Lackland, JBSA-Randolph, JBSA-Fort Sam Houston, and Camp Bullis create different commute routes. Test the route to your actual gate at the time you expect to travel.
How Should You Compare San Antonio Locations for a VA Purchase?
Compare homes by total monthly cost, condition, lot size, HOA obligations, and the commute to your actual duty location. Helotes, Boerne, Fair Oaks Ranch, Castroville, Alamo Ranch, Schertz, Cibolo, and Stone Oak offer different property types and routes. Check current listings rather than relying on an undated price range or a fixed drive-time claim.
Use our San Antonio neighborhood guides as a starting point and verify details for each property.
How Does BAH Affect Your Homebuying Budget?
BAH is one input to a household budget. It is not a mortgage approval amount. Verify the allowance for your duty ZIP code, pay grade, dependency status, and year using the Defense Travel Management Office. Ask your lender to estimate principal, interest, taxes, insurance, HOA costs, and other obligations. Allow room for maintenance and moving expenses.
How Should You Compare an Agent Found Through a Directory?
A directory can help you discover agents. Ask how it selects participants, whether a referral arrangement applies, and what it verifies. Evaluate each agent directly through current license status, relevant experience, reviews, communication, and written representation terms.
Ask the agent about recent VA-financed purchases, JBSA timelines, appraisal issues, and coordination with lenders. Compensation and representation terms are negotiable. Review any credit offer in writing before relying on it.
Meet Christopher Beal
Christopher Beal is a U.S. Army veteran, REALTOR and Military Relocation Professional with eXp Realty, TREC #723559. He leads Veteran Real Estate San Antonio: The Beal Group. His recognition includes seven eXp ICON awards and San Antonio Business Journal Top 25 Individual Agent placements (#13 in 2024, #14 in 2025, and #20 in 2026). The agency was voted Best Real Estate Agency in the San Antonio Current's 2026 Best of San Antonio Readers' Choice.
Christopher assists buyers and sellers with PCS moves, home searches, negotiations, and transaction coordination. Read his biography or request a homebuying consultation.
Frequently Asked Questions
Can I buy with no down payment?
Eligible borrowers may qualify for no down payment, subject to entitlement, lender approval, appraisal, and other requirements. No down payment does not mean no cash is needed. Review earnest money, inspections, closing costs, and prepaid items with your lender.
Can I use the benefit more than once?
Prior VA financing does not automatically prevent another purchase. Have the lender review your COE, remaining entitlement, occupancy requirements, and any restoration request. VA explains entitlement here.
What is Serve & Save?
Serve & Save is The Beal Group's closing-cost credit program for eligible veterans and active-duty buyers. The program formula uses 1% of the gross buyer-agent commission for each year of verified active service, rather than a percentage of the home's purchase price. Written program terms, brokerage requirements, lender approval, and available eligible costs govern the credit. It does not guarantee a cash payment or eliminate all closing costs. Review the program details with Christopher and your lender before relying on an amount.
How long will closing take?
Timing depends on the contract, appraisal, title work, underwriting, and document delivery. Confirm a realistic schedule with the lender and transaction team before committing to a PCS move date.
How can I contact Christopher?
Call (210) 882-8583 or request a consultation. Christopher provides real estate representation; your licensed lender determines loan eligibility, pricing, and approval.
Explore More Resources
- VA Home Loans Guide
- Military Relocation San Antonio
- Serve & Save Program
- Client Reviews
- San Antonio Homes for Sale
- Read More Blog Articles
- What Is My Home Worth?
- Contact The Beal Group
Ready to make your move? Call Christopher Beal at (210) 882-8583 or visit veteranrealestatesa.com today.
Categories
- All Blogs (354)
- Alamo Heights (4)
- awards (4)
- Best Neighborhoods in San Antonio (13)
- Buyer (16)
- Buyer Education (86)
- Community Events (4)
- Hill Country (17)
- JBSA (43)
- Local Guide (6)
- Luxury (28)
- Luxury Real Estate (26)
- Market Trends (19)
- Market Update (14)
- Military Relocation (111)
- Military Retirement (3)
- Mortgage (19)
- Neighborhood Guides (18)
- neighborhoods (5)
- New Construction (16)
- PCS (42)
- Real Estate (40)
- reviews (3)
- San Antonio (53)
- San Antonio Lifestyle (4)
- San Antonio Market (5)
- San Antonio Neighborhoods (43)
- San Antonio Real Estate (100)
- San Antonio, Veterans Resources, VA Loans (5)
- Seller (55)
- VA Home Loans (30)
- VA Loans (35)
- Va Loans & Financing (27)
- Veterans (10)
- Veterans Resources (40)
Recent Posts