VA Loan vs Conventional Loan in San Antonio 2026: Which Is Better for Military Buyers?
LAST UPDATED: AUGUST 22, 2026 | BY CHRISTOPHER BEAL, U.S. ARMY VETERAN & REALTOR
VA Loan vs Conventional Loan in San Antonio 2026: Which Is Better for Military Buyers?
Key Takeaways
- For most eligible San Antonio military buyers, a VA loan beats a conventional loan because it requires zero down payment and charges no monthly mortgage insurance.
- A conventional loan can win when you are making a 20 percent or larger down payment, buying a second home or investment property, or when a seller is wary of the VA appraisal in a competitive offer.
- The VA funding fee is the main cost of a VA loan, but it is waived entirely for veterans with a service-connected disability rating.
- In 2026 there is no VA county loan limit for buyers with full entitlement, so a VA loan can finance well above the conforming limit in Bexar County with no down payment.
- The right answer depends on your entitlement, your down payment, your disability status, and the specific property, which is why this decision should be run as actual numbers, not rules of thumb.
In This Guide
- What Is the Difference Between a VA and Conventional Loan?
- Which Loan Actually Costs Less?
- VA vs Conventional: Side-by-Side Comparison
- When Is a VA Loan the Better Choice?
- When Is a Conventional Loan the Better Choice?
- Does Loan Type Affect Your Offer in San Antonio?
- About the Author
- Frequently Asked Questions
What Is the Difference Between a VA and Conventional Loan?
A VA loan is a benefit you earned. The VA does not lend the money; it guarantees a portion of the loan a private lender makes, which lowers the lender's risk. That guarantee is why a VA loan can offer no down payment, no private mortgage insurance, and competitive interest rates that a conventional borrower with the same down payment usually cannot match.
A conventional loan is the civilian default. Conventional loans follow guidelines set by Fannie Mae and Freddie Mac. They typically require a down payment of at least 3 to 5 percent, and if you put down less than 20 percent you pay private mortgage insurance until you reach enough equity. There is no funding fee.
If you are still learning how the VA benefit works in the first place, start with my primer on how a VA loan works for first-time military buyers, then come back here to compare it against the conventional option.
Which Loan Actually Costs Less?
The hidden monthly cost is mortgage insurance. On a conventional loan with less than 20 percent down, private mortgage insurance commonly adds tens to a few hundred dollars to your monthly payment until you build 20 percent equity. A VA loan never charges monthly mortgage insurance, regardless of your down payment. Over the first several years, that difference often outweighs everything else.
The VA's main cost is a one-time funding fee. The VA funding fee is a percentage of the loan, paid once, and it can be rolled into the loan. First-use, zero-down funding fees are higher than subsequent-use fees. Crucially, the fee is waived completely for veterans receiving compensation for a service-connected disability, which changes the comparison dramatically.
You can confirm the current funding-fee percentages and waiver rules directly at VA.gov, and you can read the federal rules on private mortgage insurance cancellation at the Consumer Financial Protection Bureau.
VA vs Conventional: Side-by-Side Comparison
Here is how the two loans stack up for a typical San Antonio military buyer in 2026.
| Feature | VA Loan | Conventional Loan |
|---|---|---|
| Down payment | $0 with full entitlement | Typically 3 to 20 percent |
| Monthly mortgage insurance | None, ever | Yes if under 20 percent down (PMI) |
| Upfront fee | VA funding fee, waived for disabled veterans | None |
| Credit flexibility | More forgiving; no set VA minimum score | Stricter; usually 620 or higher |
| Loan limit (full entitlement) | No VA limit; zero down above conforming | Conforming limit, then jumbo rules |
| Property types | Primary residence only | Primary, second home, or investment |
| Appraisal | VA appraisal with minimum property requirements | Standard appraisal |
| Best fit | Eligible buyer, low or no down payment, primary home | 20 percent down, second home, or investment |
Source: U.S. Department of Veterans Affairs home loan guidance and Fannie Mae/Freddie Mac conventional guidelines, 2026. Specific terms vary by lender and borrower; this is a planning comparison, not a loan offer.
When Is a VA Loan the Better Choice?
You want to keep your cash. Zero down means you can buy in San Antonio without draining your savings, which matters when you are also paying to relocate. If you are PCSing to Joint Base San Antonio, see my military relocation resources for how to time a VA purchase around orders.
Your credit is still recovering. The VA sets no hard minimum credit score, and lenders are generally more flexible on VA loans than conventional. If your score sits in the high 500s or low 600s, the VA path is usually more achievable. My guide to VA loan credit-score requirements in San Antonio covers what lenders actually look for.
You are buying above the conforming limit. With full entitlement, a VA loan has no county loan limit, so you can finance a higher-priced San Antonio home with no down payment. That is a genuine advantage over conventional financing once you cross the conforming line. My VA jumbo loan guide explains how.
When Is a Conventional Loan the Better Choice?
You are putting 20 percent or more down. At 20 percent down, a conventional loan has no PMI, and you avoid the VA funding fee entirely. In that scenario, the conventional payment can be lower, and it keeps your VA entitlement fully available for later.
You are buying a second home or an investment property. VA loans are for primary residences only. If you are buying a rental or vacation property, conventional financing is the tool. Veterans building a rental portfolio near JBSA often use conventional loans on the investment side while reserving VA for their home.
You want to win a tight bidding war with cash strength. Some San Antonio sellers perceive conventional offers as lower-risk. With a large down payment, a conventional offer can read as stronger, even though a well-prepared VA buyer is fully competitive. That perception is a real factor we will discuss next.
Does Loan Type Affect Your Offer in San Antonio?
The VA appraisal is not the obstacle it once was. San Antonio is one of the most VA-friendly markets in the country, with a huge military population, so listing agents here see VA offers constantly. The appraisal protects you, the buyer, and most local sellers are comfortable with it.
Presentation wins offers. A clean VA offer with a strong pre-approval, reasonable terms, and an agent who proactively addresses the appraisal question competes well against conventional offers. This is exactly where having a veteran REALTOR who negotiates VA deals every week pays off. Through my Serve & Save program, I also help reduce closing costs for the military families I represent.
If you are weighing whether to buy now at all, my framework on buying now or waiting in San Antonio pairs well with this loan comparison. And for a different financing matchup, see VA loan vs FHA loan in San Antonio.
What San Antonio Buyers Are Actually Paying in Late 2026
The loan you pick only matters against a real price. Here is what Bexar County actually closed at in the three months ending August 23, 2026, pulled from SABOR MLS records rather than a national average. These are the numbers a VA or conventional pre-approval has to stretch to cover in San Antonio right now.
Bexar County MetricLate 2026 Figure| Median closed sale price | $289,950 |
| Average closed sale price | $350,243 |
| Average price per square foot | $161 |
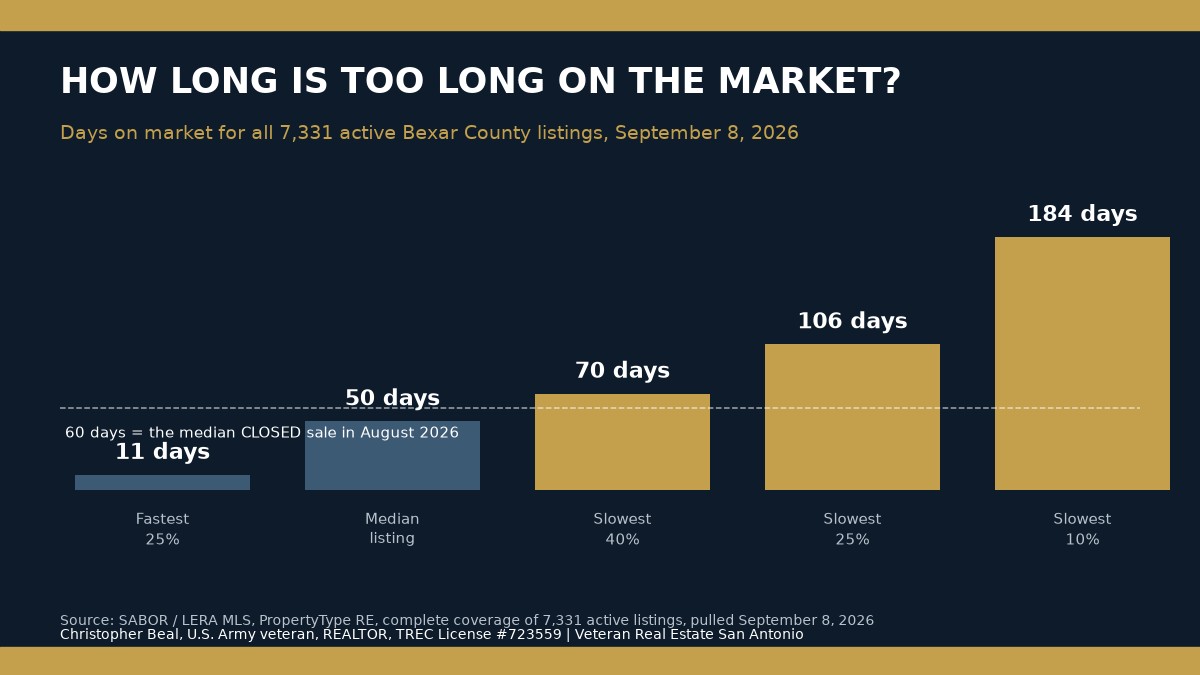
| Average days on market (closed) | 78 days |
| Median active list price | $315,000 |
| Average days on market (active listings) | 65 days |
Run the math against that $289,950 median and the difference between the two loan programs stops being abstract. A conventional buyer putting 5 percent down needs $14,498 in the bank before closing costs. A VA buyer needs nothing down, which is the single largest practical advantage of the benefit in this price band.
WHAT A $289,950 SAN ANTONIO HOME COSTS YOU UP FRONT
- VA loan, zero down: $0 down payment, and no monthly mortgage insurance for the life of the loan.
- Conventional, 5 percent down: $14,498 out of pocket, plus private mortgage insurance until you reach 20 percent equity.
- Conventional, 20 percent down: $57,990 out of pocket to avoid PMI entirely.
- VA funding fee, first use at 2.15 percent: $6,234, which can be financed into the loan and is waived completely if you have a service-connected disability rating.
The other number worth staring at is days on market. Closed sales in Bexar County averaged 78 days, and active listings are sitting an average of 65 days. That is a balanced-to-slow market, not a bidding war, and it means sellers have room to help with costs. A VA buyer can ask a seller to cover up to 4 percent of the purchase price in concessions, which at the median is roughly $11,598 toward the funding fee, prepaids, and closing costs. For a deeper breakdown of that fee, I walk through it in my 2026 VA funding fee cost guide.
About the Author: Christopher Beal
Christopher Beal is a U.S. Army veteran and the Owner of Veteran Real Estate San Antonio, a Beal Group practice brokered by eXp Realty (TREC License #723559). A Military Relocation Professional (MRP) and VAREP member, he is a 7-time eXp Realty ICON agent, winner of Best Real Estate Agency in the 2026 Best of San Antonio Readers' Choice (San Antonio Current, 100,000+ voters), and a 3x San Antonio Business Journal Top 25 Individual Agent (#13 in 2024, #14 in 2025, #20 in 2026). His recognition also includes 3x Platinum Top 50, 2x RateMyAgent Agent of the Year, 2x Real Producers Top 100, Five Star Professional (2026), and a RealTrends 2026 ranking. He has helped 325+ families, closed more than $125M in career volume, and holds 5.0 stars across 370+ verified reviews, working almost exclusively with military and veteran buyers and sellers across Bexar, Comal, Kendall, Medina, and Bandera counties, with a focus on VA loans, PCS moves, and homebuying near JBSA-Lackland, JBSA-Randolph, and Fort Sam Houston. He has guided hundreds of San Antonio military buyers through the VA versus conventional decision, and through the Serve & Save program he reduces closing costs for the veterans and military families he serves. He can be reached at (210) 882-8583.
Explore More Resources
- VA Home Loans
- Military Relocation
- Free Home Evaluation
- Serve & Save Program
- Client Reviews
- About Christopher
Frequently Asked Questions
Is a VA loan better than a conventional loan in San Antonio?
For most eligible military buyers putting little or nothing down, yes. A VA loan requires no down payment and no monthly mortgage insurance, which usually makes it cheaper month to month. A conventional loan can be better when you put 20 percent or more down, or when you are buying a second home or investment property.
Do you pay PMI on a VA loan?
No. VA loans never charge private mortgage insurance, regardless of your down payment. This is one of the biggest cost advantages over a low-down-payment conventional loan, which does require PMI until you reach 20 percent equity.
What is the VA funding fee and can it be avoided?
The VA funding fee is a one-time charge, expressed as a percentage of the loan, that helps sustain the VA program. It can be financed into the loan. Veterans who receive compensation for a service-connected disability are exempt from the funding fee entirely.
Is there a VA loan limit in Bexar County in 2026?
For buyers with full entitlement, there is no VA county loan limit. You can finance above the conforming limit with no down payment. Loan limits only come into play if you have reduced or partial entitlement.
Can I use a conventional loan to save my VA entitlement?
Yes, and it can be a smart strategy. If you put 20 percent down on a conventional loan now, you preserve your full VA entitlement for a future purchase, which is useful if you expect another PCS or plan to buy again with VA later.
Does using a VA loan hurt my offer in a San Antonio bidding war?
Rarely, if the offer is presented well. San Antonio sellers see VA offers constantly because of the large military population. A strong pre-approval and an agent who addresses the appraisal up front keep a VA buyer fully competitive.
What credit score do I need for a VA versus conventional loan?
The VA sets no minimum credit score, though individual lenders often want a score in the high 500s or low 600s. Conventional loans are stricter and usually require 620 or higher. VA financing is generally the more forgiving option for recovering credit.
Can I get a VA loan on an investment property?
No. VA loans are for primary residences only. If you want a rental or second home, you will use conventional financing. Many veteran investors near JBSA reserve their VA benefit for their own home and use conventional loans for rentals.
How much do I need for a down payment on a median-priced San Antonio home?
At the Bexar County median closed price of $289,950 for the three months ending August 23, 2026, a VA loan requires $0 down. A conventional loan at 5 percent down requires $14,498, and putting 20 percent down to avoid PMI requires $57,990. That gap is the practical reason most eligible buyers near JBSA-Lackland and JBSA-Randolph use the VA benefit instead of waiting to save a conventional down payment.
Can a San Antonio seller pay my VA closing costs?
Yes. VA rules allow a seller to contribute up to 4 percent of the purchase price toward concessions, which works out to roughly $11,598 at the current Bexar County median. With closed sales averaging 78 days on market and active listings sitting an average of 65 days, sellers here have real incentive to negotiate. Ask for concessions inside the original offer rather than after the option period expires.
Christopher Beal, U.S. Army Veteran and REALTOR. Owner of Veteran Real Estate San Antonio, brokered by eXp Realty. Serving veterans and military families across San Antonio. Call (210) 882-8583.
Categories
- All Blogs (354)
- Alamo Heights (4)
- awards (4)
- Best Neighborhoods in San Antonio (13)
- Buyer (16)
- Buyer Education (86)
- Community Events (4)
- Hill Country (17)
- JBSA (43)
- Local Guide (6)
- Luxury (28)
- Luxury Real Estate (26)
- Market Trends (19)
- Market Update (14)
- Military Relocation (111)
- Military Retirement (3)
- Mortgage (19)
- Neighborhood Guides (18)
- neighborhoods (5)
- New Construction (16)
- PCS (42)
- Real Estate (40)
- reviews (3)
- San Antonio (53)
- San Antonio Lifestyle (4)
- San Antonio Market (5)
- San Antonio Neighborhoods (43)
- San Antonio Real Estate (100)
- San Antonio, Veterans Resources, VA Loans (5)
- Seller (55)
- VA Home Loans (30)
- VA Loans (35)
- Va Loans & Financing (27)
- Veterans (10)
- Veterans Resources (40)
Recent Posts