VA Certificate of Eligibility (COE) in 2026: How San Antonio Military Buyers Get Approved Faster
LAST UPDATED: SEPTEMBER 19, 2026 | BY CHRISTOPHER BEAL, U.S. ARMY VETERAN & REALTOR
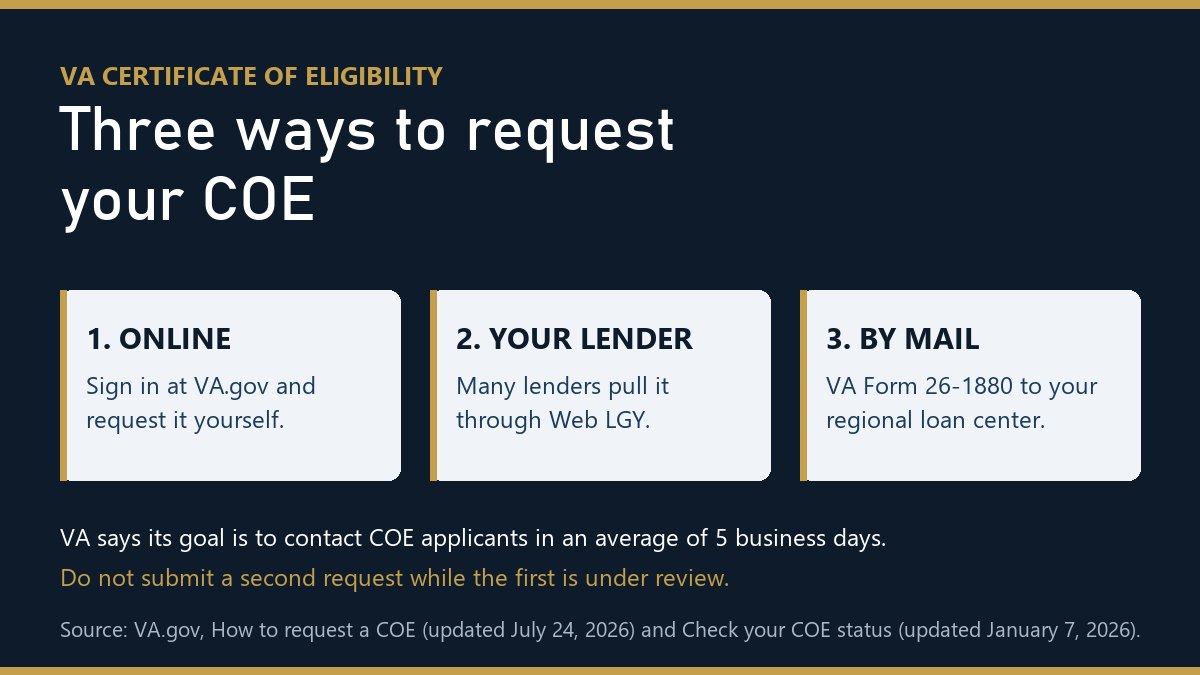
Quick answer: You do not need a VA Certificate of Eligibility in hand to start touring San Antonio homes, but you do need one before a VA loan can close, and most lenders want it before they will issue a preapproval letter a seller takes seriously. You can request it online at VA.gov, through your lender's Web LGY system, or by mail on VA Form 26-1880, and VA says its goal is to contact COE applicants in an average of 5 business days.
I am Christopher Beal, a U.S. Army veteran, REALTOR (TREC License #723559) and Owner of Veteran Real Estate San Antonio, brokered by eXp Realty. More about my background and how I work.
KEY TAKEAWAYS
- The COE proves your VA home loan entitlement to a lender. It is not a preapproval, a credit decision or a loan limit.
- A COE showing basic entitlement of $36,000 means full entitlement, which means no VA loan limit. Your lender's approval and the appraised value still cap the actual loan.
- VA sets no minimum credit score. Individual lenders do, which is why two lenders can give you two different answers on the same COE.
- If you have a VA loan you have not paid off, your remaining entitlement is calculated against the county one-unit loan limit, and you may need a down payment.
- In Bexar County, 5,624 of the 5,824 residential sales that closed from June 14 to September 12, 2026 closed at or below the 2026 baseline one-unit loan limit of $832,750, so for most local buyers with full entitlement the limit is not the binding constraint.
IN THIS GUIDE
- What is a VA Certificate of Eligibility, and do I need one before I look at homes?
- What documents do I need before I request a COE?
- How do I request my COE?
- How long does a COE take?
- What does my COE actually tell the lender?
- What if I have used my VA loan before?
- Does the county loan limit actually bind in San Antonio?
- Does my COE affect the VA funding fee?
- What should I do the week my COE arrives?
- Frequently asked questions
What is a VA Certificate of Eligibility, and do I need one before I look at homes?
The COE is a document from VA that confirms to a lender that you qualify for the VA home loan benefit and how much entitlement you have. You can tour homes without it, but you cannot close a VA loan without it.
The COE answers one question: does this borrower have VA home loan entitlement, and how much. VA describes requesting a COE as the first step in getting a VA-backed home loan. It is not a statement about your credit, your income or the price of a house.
That distinction matters in a market like San Antonio, where listing agents read preapproval letters closely. A COE alone will not get your offer accepted. A lender's preapproval, built on the COE plus your credit and income, is what carries weight.
Practically, the order that works is: request the COE, give it to the lender you have chosen, get the preapproval letter, then start writing offers. If you are already touring homes and have not requested the COE yet, request it today and keep touring. The two things run in parallel.
What documents do I need before I request a COE?
It depends on your status: a DD214 if you have separated, a signed statement of service if you are currently serving, and specific Guard or Reserve paperwork if you were never activated.
Gathering the right document first is the single biggest time saver. VA lists what it needs by category:
| Your status | What VA asks for |
|---|---|
| Veteran | A copy of your discharge or separation papers (DD214) |
| Active-duty service member | A statement of service signed by your commander, adjutant or personnel officer showing your full name, Social Security number, date of birth, date you entered duty, duration of any lost time, and the name of the command providing the information |
| Current or former activated National Guard member | A DD214 or other discharge documents. With at least 90 days of active-duty service including at least 30 consecutive days, a DD214 showing 32 USC 316, 502, 503, 504 or 505 activation, or an annual point statement, or a DD220 with accompanying orders |
| Current or former activated Reserve member | A DD214 or other discharge documents |
| Guard or Reserve member, never activated, still serving | A signed statement of service that also shows your total number of creditable years of service |
| Discharged Guard member, never activated | NGB Form 22 for each period of service, plus NGB Form 23 and proof of the character of service |
| Discharged Reserve member, never activated | A copy of your latest annual retirement points, plus proof of honorable service |
| Surviving spouse receiving DIC | VA Form 26-1817, plus the veteran's DD214 if available |
| Surviving spouse not receiving DIC | A completed VA Form 21P-534EZ, a copy of the marriage license, and the veteran's death certificate |
Source: VA.gov, How to request a VA home loan Certificate of Eligibility (COE), last updated July 24, 2026. Scope: all U.S. applicants, not San Antonio specific.
If you are serving at JBSA-Lackland, JBSA-Randolph or Fort Sam Houston and need a statement of service, that request goes through your unit's personnel office. Ask for it before you start the COE request, not after.
Guard and Reserve eligibility has its own wrinkles worth reading separately: National Guard and Reserve VA loan eligibility in San Antonio.
How do I request my COE?
Three ways: online at VA.gov, through your lender's Web LGY system, or by mail on VA Form 26-1880 sent to your regional loan center.
Most San Antonio buyers I work with use the lender route or the online route. Here is what each one is actually good for.
- Online at VA.gov. You sign in and request it yourself. VA says that in many cases it has enough information to determine eligibility automatically and give you a downloadable COE. Start the request on VA.gov.
- Through your lender. Your lender may be able to use an online system called Web LGY to pull the COE. Ask whether they can. This is usually the fastest path when your record is straightforward, and it puts the document directly in the file that needs it.
- By mail. Fill out VA Form 26-1880 and mail it to the address for your regional loan center, which is printed on the last page of the form. VA notes that mail requests may take longer than the online or lender routes.
There is no penalty for asking your lender to try Web LGY while you also request online. What you should not do is submit a second COE request while one is already under review. VA states plainly that submitting a new request will not affect the decision or make the process go faster.
Not sure which lender to hand your COE to? See how I walk veterans through the VA loan process in San Antonio.
How long does a COE take?
VA states that its goal for contacting home loan COE applicants is an average of 5 business days. That is a stated goal for making contact, not a guaranteed issue date.
Read that number for what it is. VA publishes it as an average goal for contacting applicants, and it tells applicants not to submit another request even if their own case takes longer than 5 business days. Some records resolve instantly online. Some need a document VA does not have yet.
You can sign in and check where your request sits in the review process, read letters VA has sent about it, upload additional supporting documents, and download the COE if VA approves it. Check your COE status on VA.gov.
If VA denies the request, there is a decision review process. That is not the end of the road, and it is worth telling your lender immediately rather than letting a contract timeline run against you.
What does my COE actually tell the lender?
It shows your basic entitlement and any prior loans charged to entitlement. A basic entitlement of $36,000 means full entitlement and no VA loan limit, subject to lender approval and the appraisal.
The number most people fixate on is $36,000, and almost everyone misreads it. VA is explicit: $36,000 is not the amount you can borrow. It is the maximum VA will pay your lender if you default on a loan of $144,000 or less. Above $144,000, VA guarantees up to 25 percent of the loan amount.
What a COE showing basic entitlement of $36,000 does mean is that you have full entitlement, and with full entitlement there is no VA loan limit. VA states this directly. If you see a fixed dollar VA loan limit quoted for a full-entitlement borrower anywhere, that source is out of date.
Two constraints still apply, and they are the ones that decide your actual purchase price:
- Lender approval. Your lender sizes the loan from your credit history, income, debts and assets.
- The appraisal. VA states the maximum loan on an individual property is either the appraised value or the purchase price, whichever is lower. VA's own example: preapproved to $450,000, contract at $400,000, appraisal at $375,000, and the loan is capped at $375,000.
One more thing worth knowing before you shop lenders: VA does not require a minimum credit score. Some lenders do. That is a lender overlay, not a VA rule, and it is exactly why VA suggests contacting more than one lender to compare. A "no" from one lender on the same COE is not a "no" from the VA benefit.
If you are working out whether your income supports the payment, the residual income test is the VA-specific piece most buyers have never heard of: VA loan residual income and DTI requirements in San Antonio.
What if I have used my VA loan before?
Your COE lists prior loans charged to entitlement. If you still have entitlement tied up in a loan you have not paid off, your remaining bonus entitlement is measured against the county one-unit loan limit, and a down payment may be required.
This is the situation most PCS repeat buyers land in. You bought near a previous duty station, you kept the house or have not sold yet, and part of your entitlement is still charged. VA's own method for what is left:
- On your COE, find the "Prior Loans charged to entitlement" table and read the Entitlement Charged column.
- Look up the one-unit loan limit for the county where the property is located, on the FHFA conforming loan limit list. Use the One-Unit Limit even if the property has more than one unit.
- Multiply that One-Unit Limit by 0.25.
- Subtract the entitlement you have already used. What is left is your remaining bonus entitlement.
VA adds that most lenders require your entitlement, your down payment, or a combination of the two to cover at least 25 percent of the total loan amount, and that multiplying your remaining bonus entitlement by 4 gives the maximum most lenders would loan without a down payment.
ILLUSTRATIVE WORKED EXAMPLE (not a quote, not an approval)
Inputs: $50,000 of entitlement already charged on a prior loan, and the 2026 baseline one-unit conforming loan limit value of $832,750 announced by FHFA on November 25, 2025. Confirm the actual one-unit limit for your county on FHFA's 2026 list before you rely on this math.
- $832,750 x 0.25 = $208,187.50
- $208,187.50 minus $50,000 already used = $158,187.50 remaining bonus entitlement
- $158,187.50 x 4 = $632,750, the approximate maximum loan most lenders would write with no down payment
This is arithmetic on published inputs, not a loan offer. Your lender still has to approve you, and the appraisal still caps the loan. I am a REALTOR, not a lender or a financial advisor.
Restoring entitlement is its own decision, and it usually shows up when the next set of orders does: a second VA loan, an assumption, or selling: the entitlement math for your next PCS.
Does the county loan limit actually bind in San Antonio?
For the large majority of local purchases, no. Over the last full quarter of Bexar County closings, 96.6 percent of sales closed at or below the 2026 baseline one-unit limit of $832,750.
I pulled the actual closings rather than repeat a rule of thumb. Here is the count, with complete coverage of the filter set verified by paging the result to exhaustion.
| Bexar County residential closings, June 14 to September 12, 2026 | Count | Share |
|---|---|---|
| All closings in the filter set | 5,824 | 100% |
| Closed at or below $832,750 | 5,624 | 96.6% |
| Closed above $832,750 | 200 | 3.4% |
Source: SABOR / LERA MLS via the RESO Web API, pulled September 13, 2026. Filters: CountyOrParish BEXAR, MlsStatus SLD, PropertyType RE, CloseDate from 2026-06-14 through 2026-09-12. Coverage is complete for that filter set: the result was paged to exhaustion at 5,824 records, and the above-limit subset was paged to exhaustion at 200. Units are closed sale prices in U.S. dollars. Comparison value is the FHFA 2026 baseline one-unit conforming loan limit of $832,750; confirm Bexar County's own one-unit limit on FHFA's 2026 county list.
The practical reading: if you have full entitlement, the loan limit is almost never the thing standing between you and a San Antonio house. Your debt-to-income ratio, your residual income and the appraisal are. If you are in the 3.4 percent band shopping above $832,750, or you have partial entitlement, then the limit math in the previous section is worth doing carefully with your lender.
Does my COE affect the VA funding fee?
Yes. Your COE is where the lender sees whether this is a first or subsequent use of the benefit, and exemption status is confirmed against VA records rather than assumed.
The funding fee is a one-time payment, and a lot of San Antonio buyers qualify to skip it entirely. VA lists the exemptions: you are receiving VA compensation for a service-connected disability; you are eligible to receive that compensation but take retirement or active-duty pay instead; you receive Dependency and Indemnity Compensation as a surviving spouse; you are a service member with a proposed or memorandum rating before the loan closing date from a pre-discharge claim; or you are an active-duty member who provides evidence of a Purple Heart on or before the closing date.
If a rating comes through after closing, VA states you still owe the fee and are not eligible for a refund on that basis. If compensation is later awarded with an effective date retroactive to before your closing, a refund may be available.
| VA-backed purchase loan | Down payment | Funding fee |
|---|---|---|
| First use | Less than 5% | 2.15% |
| First use | 5% or more | 1.5% |
| First use | 10% or more | 1.25% |
| After first use | Less than 5% | 3.3% |
| After first use | 5% or more | 1.5% |
| After first use | 10% or more | 1.25% |
Source: VA.gov, VA funding fee and loan closing costs, rate charts effective April 7, 2023, page last updated January 15, 2026. Rates are a percentage of the total loan amount, for veterans, active-duty service members, and National Guard and Reserve members. Refinance, NADL, IRRRL, assumption and manufactured-home rates differ.
Two details that change offers in practice. First, the fee applies to the loan amount, not the purchase price. Second, VA allows sellers and builders to credit closing costs, and limits seller concessions to no more than 4 percent of the home's reasonable value as shown on the VA Notice of Value. On a purchase loan you can finance the funding fee into the loan, but VA states you must pay all other fees and charges at closing.
My Serve & Save program is a closing-cost credit for the veterans and service members I represent as a buyer's agent, equal to 1 percent of my gross buyer-agent commission for each verified year of active-duty service. It is subject to lender approval and is shown on the Closing Disclosure. It is separate from the VA funding fee, and it can stack with a negotiated seller credit. How Serve & Save works.
What should I do the week my COE arrives?
Send it to your lender, read the entitlement line yourself, get the preapproval letter dated, and confirm the funding fee status in writing before you write an offer.
This is the sequence I run with veteran buyers here, in order.
- Send the PDF to your lender the day you get it. Not a screenshot. The file.
- Read the basic entitlement line and the prior loans table yourself. If the prior loans table shows a loan you have already paid off and sold, say so to the lender now, not two weeks into a contract.
- Ask the lender, in writing, whether they are treating you as funding-fee exempt and why. Exemption status changes your cash to close and your loan amount.
- Get the preapproval letter with a current date and a dollar amount you are actually comfortable with. The letter is what goes with the offer, and a stale date reads as a stale buyer.
- Compare a second lender before you commit. VA does not set a credit score minimum, so the overlays are the lender's. One conversation can move your rate, your fee credit or your approval.
- Then start writing offers. With the COE, the preapproval and the fee question settled, your offer can compete on terms instead of on hope.
If you are timing this against orders, the PCS calendar drives everything else: how I handle PCS moves into San Antonio.
Have your COE and want to know what it buys in this market? Call or text me at (210) 882-8583.
About the Author: Christopher Beal
Christopher Beal is a U.S. Army veteran and the Owner of Veteran Real Estate San Antonio, a Beal Group practice brokered by eXp Realty (TREC License #723559). A Military Relocation Professional (MRP) and VAREP member, he is a 7-time eXp Realty ICON agent, winner of Best Real Estate Agency in the 2026 Best of San Antonio Readers' Choice (San Antonio Current, 100,000+ voters), and a 3x San Antonio Business Journal Top 25 Individual Agent (#13 in 2024, #14 in 2025, #20 in 2026). His recognition also includes 3x Platinum Top 50, 2x RateMyAgent Agent of the Year, 2x Real Producers Top 100, Five Star Professional (2026), and a RealTrends 2026 ranking. He has helped 325+ families, closed more than $125M in career volume, and holds 5.0 stars across 370+ verified reviews, working almost exclusively with military and veteran buyers and sellers across Bexar, Comal, Kendall, Medina, and Bandera counties, with a focus on VA loans, PCS moves, and homebuying near JBSA-Lackland, JBSA-Randolph, and Fort Sam Houston. He reads COEs with clients before they write offers, because the entitlement line and the funding fee question decide more San Antonio deals than most buyers expect. He can be reached at (210) 882-8583.
Frequently asked questions
Do I need my COE before I start looking at houses in San Antonio?
No. You can tour homes without it. You cannot close a VA loan without it, and most lenders want it before issuing the preapproval letter that goes with your offer, so request it as early as you can and keep looking in the meantime.
How long does a VA COE take to come back?
VA states that its goal for contacting home loan COE applicants is an average of 5 business days. That is a stated goal for making contact, not a guaranteed issue date. VA also asks that you not submit another request while one is under review, even if yours takes longer.
My COE says my basic entitlement is $36,000. Can I only borrow $36,000?
No. VA states that $36,000 is not the amount you can borrow. It is the maximum VA would pay your lender if you defaulted on a loan of $144,000 or less. A basic entitlement of $36,000 means you have full entitlement and no VA loan limit, though your lender still has to approve you and the loan is capped at the appraised value or the purchase price, whichever is lower.
Is there a minimum credit score for a VA loan?
VA does not require a minimum credit score. Individual lenders set their own minimums, which is why VA suggests contacting more than one lender to compare. A decline from one lender is a lender decision, not a VA eligibility decision.
I already have a VA loan on a house near my last duty station. Can I get another one?
Possibly, using remaining bonus entitlement. Your COE shows the entitlement already charged. The remaining amount is calculated against the county one-unit loan limit from the FHFA list, and most lenders want entitlement, down payment, or both to cover at least 25 percent of the new loan. A down payment may be required.
Does everyone pay the VA funding fee?
No. VA lists exemptions including veterans receiving VA compensation for a service-connected disability, those eligible for that compensation but receiving retirement or active-duty pay instead, surviving spouses receiving Dependency and Indemnity Compensation, service members with a proposed or memorandum rating before closing from a pre-discharge claim, and active-duty members who provide evidence of a Purple Heart on or before the closing date. Confirm your status with your lender in writing.
Can my lender get the COE for me?
Often, yes. VA states your lender may be able to use an online system called Web LGY to obtain it. Ask your loan officer directly. It is usually the quickest route when your service record is straightforward.
What if VA denies my COE request?
You can request a decision review. Tell your lender and your agent right away so contract deadlines are not running against a request that is still being resolved.
EXPLORE MORE RESOURCES
GET MORE INFORMATION
Bring me your COE and your timeline. I will tell you what it means for the houses you are actually looking at in Bexar, Comal, Kendall, Medina or Bandera county, and what to fix before you write an offer.
Categories
- All Blogs (355)
- Alamo Heights (4)
- awards (4)
- Best Neighborhoods in San Antonio (13)
- Buyer (16)
- Buyer Education (86)
- Community Events (4)
- Hill Country (17)
- JBSA (44)
- Local Guide (6)
- Luxury (28)
- Luxury Real Estate (26)
- Market Trends (19)
- Market Update (14)
- Military Relocation (112)
- Military Retirement (3)
- Mortgage (19)
- Neighborhood Guides (19)
- neighborhoods (5)
- New Construction (16)
- PCS (42)
- Real Estate (40)
- reviews (3)
- San Antonio (53)
- San Antonio Lifestyle (4)
- San Antonio Market (5)
- San Antonio Neighborhoods (44)
- San Antonio Real Estate (100)
- San Antonio, Veterans Resources, VA Loans (5)
- Seller (55)
- VA Home Loans (30)
- VA Loans (35)
- Va Loans & Financing (27)
- Veterans (10)
- Veterans Resources (40)
Recent Posts