San Antonio Home Appraisals 2026: Cost, Timeline, VA Rules
LAST UPDATED: AUGUST 21, 2026 | BY CHRISTOPHER BEAL, U.S. ARMY VETERAN & REALTOR
A home appraisal is an independent, licensed opinion of what your San Antonio home is worth on the open market, and it is the single number that can hold a deal together or blow it apart. Whether you are selling in Stone Oak, buying with a VA loan near JBSA-Lackland, or refinancing in Helotes, the appraisal is the moment your price stops being an opinion and starts being a fact your lender will fund against.
I have walked more than 325 San Antonio families through this step, and the pattern is always the same: the people who understand the appraisal before it happens almost never get surprised by it. The people who treat it as paperwork are the ones renegotiating at the last minute.
Key Takeaways
- A San Antonio appraisal typically costs $450 to $900 in 2026, paid by the buyer at or before closing.
- Expect 7 to 21 days from lender order to final report. VA appraisals in Bexar County usually run 7 to 12 days.
- Bexar County homes sold over the last 90 days closed at an average of $161 per square foot, while active listings are asking an average of $168 per square foot. That 4 percent gap is where low appraisals live.
- When an appraisal comes in low you have exactly four moves: renegotiate, bridge the gap in cash, dispute with better comparable sales, or walk under your contingency.
- VA buyers get a protection nobody else gets: the Tidewater Initiative, which lets your agent submit comparable sales before the appraiser finalizes a low number.
What a San Antonio Home Appraisal Actually Is (and What It Is Not)
An appraisal is a licensed professional's written opinion of market value, ordered by your lender, not by you. The appraiser works for the lender's interest, which is making sure the bank is not lending $400,000 against a house worth $360,000.
Texas appraisers are licensed by the Texas Appraiser Licensing and Certification Board (TALCB) and must follow the Uniform Standards of Professional Appraisal Practice (USPAP). Your lender almost always orders through an Appraisal Management Company (AMC), which is a deliberate firewall so nobody in the transaction can lean on the appraiser.
The three things people constantly confuse are the appraisal, the inspection, and the CMA. They answer completely different questions.
| Appraisal | Home Inspection | CMA | |
|---|---|---|---|
| Question it answers | What is it worth? | What is wrong with it? | What should we list or offer? |
| Who orders it | The lender | The buyer | Your agent |
| Typical 2026 cost | $450 to $900 | $350 to $600 | No charge from me |
| Binding on the loan | Yes | No | No |
If you want the buyer-side version of this comparison in detail, I broke it out in VA appraisal vs. home inspection in San Antonio.
What Appraisals Cost in San Antonio in 2026
Budget $450 to $900 for a standard single-family appraisal in Bexar County, and expect the higher end for anything unusual. Cost has drifted up over the last two years as AMC fees and appraiser scheduling pressure increased.
What pushes you toward the top of the range is rarely the price of the house. It is complexity. Acreage in Bandera County, a 1920s bungalow in Alamo Heights with no clean comparable sales, a barndominium outside Boerne, or a home with a converted garage and unpermitted square footage all take longer to value defensibly.
- Standard suburban home (Alamo Ranch, Converse, Schertz, Cibolo): $450 to $600
- Larger or custom home ($600K and up, Stone Oak, The Dominion): $650 to $900
- Rural or acreage (Medina, Bandera, Kendall counties): $700 to $1,200
- FHA or VA appraisal: similar range, though VA fees are set by the Department of Veterans Affairs regional schedule
- Desk or drive-by review (some refinances): $150 to $350
The buyer pays for the appraisal in nearly every San Antonio transaction, usually as an up-front charge to the lender rather than a closing cost rolled into settlement. Sellers do not pay for it, but sellers absolutely live with the result.
The Appraisal Timeline, Step by Step
From the day your lender orders it, plan on 7 to 21 days to a final report. Here is what is actually happening in that window.
- Order and assignment (day 1 to 3). The lender submits to an AMC, which shops the assignment to appraisers licensed for that county and product type.
- Research (day 2 to 5). The appraiser pulls Bexar Appraisal District records, deed history, and closed sales from the San Antonio MLS through SABOR.
- Site visit (day 4 to 10). Thirty minutes to two hours on site. The appraiser measures exterior dimensions, sketches the floor plan, counts bedrooms and full baths, photographs every room, and notes condition and updates.
- Analysis and reconciliation (day 6 to 14). Usually three to six closed comparable sales, adjusted for square footage, lot size, age, condition, garage bays, pool, and location.
- Report delivery (day 10 to 21). A 10 to 30 page report goes to the lender first. Federal rules require the lender to give the buyer a copy, but that copy sometimes lags by a couple of days.
Two San Antonio specific timing notes. First, appraiser capacity tightens every spring, so a March or April contract can add a week. Second, if the property sits in Comal or Kendall County where the appraiser pool is thinner, build in extra runway before you commit to a tight closing date.
What Bexar County Sales Data Says About Appraisal Risk Right Now
The clearest signal in the current market is the gap between what sellers are asking per square foot and what buyers are actually closing at. I pulled the numbers from SABOR MLS for this update.
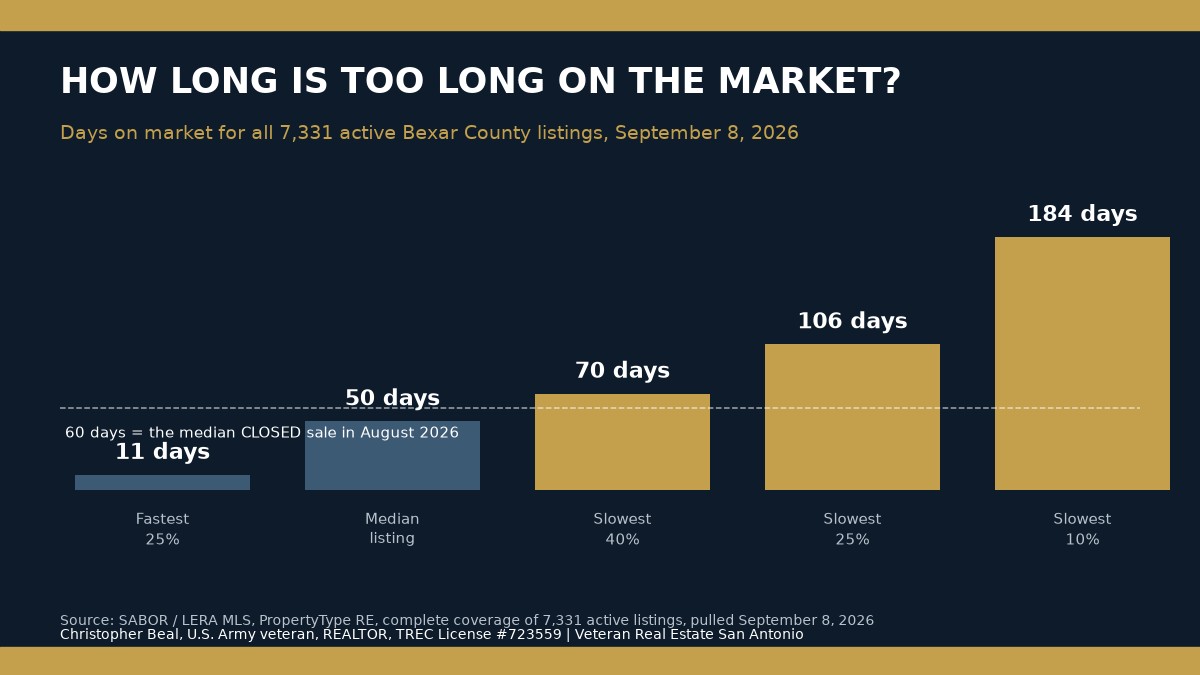
Across the 90 days ending August 21, 2026, Bexar County closed sales showed a median close price of roughly $287,700 and an average close price near $349,000, at an average of $161 per square foot, with sold homes averaging about 77 days on market.
Meanwhile, active Bexar County inventory carries a median list price near $283,750 and an average asking price of about $168 per square foot.
"Sellers in Bexar County are asking about four percent more per square foot than buyers are actually paying. That spread is not a rounding error. It is the exact space where low appraisals happen."
Christopher Beal, Owner, Veteran Real Estate San Antonio
Practically, that means two things. If you are a seller pricing off what your neighbor is asking rather than what the block actually closed at, you are pricing into appraisal risk. If you are a buyer writing over list in a multiple-offer situation, you need to know in advance whether you can cover a shortfall in cash.
It also means the 77 day average market time is doing real work. Homes that need 77 days to sell are not homes with runaway appreciation supporting an aggressive number. I go deeper on the pricing mechanics in how to price your home in San Antonio.
What Appraisers Actually Measure in San Antonio
Appraisers weigh a short list of factors heavily and almost everything else lightly. Knowing the difference tells you where to spend money before the visit and where not to.
Heavy weight: gross living area in finished, permitted, heated and cooled square footage; bedroom and full bath count; lot size; year built and effective age; garage bays; and above all, the closed comparable sales within roughly a mile and the last six months.
Moderate weight: condition of roof, HVAC, and foundation; kitchen and bath updates; pool; covered outdoor living; energy efficiency such as solar and radiant barrier; and school attendance zone, which matters enormously around Alamo Heights ISD and the North East ISD Stone Oak schools.
Light weight: paint colors, staging, furniture, landscaping beyond basic upkeep, and personal upgrades that do not add measurable square footage or system life.
Two San Antonio specifics deserve their own line. Foundation movement is the single most common value hit in this market because of our expansive clay soils, and documented, engineer-signed repair work is worth far more at the appraisal than an undocumented "we had it looked at." Flood zone designation near the San Antonio River and Salado Creek can move value and will absolutely move insurability.
If your home has known foundation history, read selling a San Antonio home with foundation problems before you list.
VA Appraisals: MPRs, Tidewater, and the Escape Clause
A VA appraisal does two jobs at once: it establishes value and it certifies the home meets the VA's Minimum Property Requirements. That second job is why VA appraisals get a reputation for being tough, and it is why the appraiser is assigned from a VA panel rather than chosen by the lender.
The Minimum Property Requirements are safety and habitability standards, not cosmetic ones. In practice, around JBSA-Lackland, JBSA-Randolph, and Fort Sam Houston, the items that get flagged most often are peeling paint on pre-1978 homes, missing handrails, non-functioning HVAC, active roof leaks, exposed wiring, and standing water in a crawlspace.
Three protections exist that most veteran buyers never hear about until it is too late.
- The Tidewater Initiative. If the appraiser is heading toward a value below the contract price, the VA requires notice to the listing agent, who then has 48 hours to submit additional comparable sales and supporting data. This is the one real chance to influence the number before it is final, and it only works if your agent answers the phone and has comps ready.
- The VA Amendatory Escape Clause. Federal law puts this in every VA purchase contract. If the Notice of Value comes in below the contract price, the buyer may walk and keep the earnest money, with no separate appraisal contingency required.
- Reconsideration of Value. Even after a Notice of Value is issued, a documented ROV with better comparable sales can move the number.
VA appraisal turnaround in Bexar County typically runs 7 to 12 days, faster than the national average, because San Antonio has one of the deepest VA appraiser panels in the country. The official VA requirements are published at benefits.va.gov/homeloans, and Texas appraiser licenses can be verified through TALCB.
How to Prepare Your Home for the Appraiser
You cannot change your comparable sales, but you can absolutely change what the appraiser records about condition and square footage. This is a two-hour job that routinely protects thousands of dollars.
- Hand over a documented improvement list. Dates, costs, and contractor names for roof, HVAC, water heater, windows, foundation, and kitchen or bath work. Receipts beat memory.
- Produce permits and engineer letters. A permitted, engineer-signed foundation repair is a stabilized home. An unpermitted one is a defect.
- Make sure every space is measurable and accessible. Unlock gates, clear the attic access, clear the electrical panel and water heater closet, and move vehicles out of the garage so bays can be counted.
- Confirm the square footage on record is right. Bexar Appraisal District records are wrong more often than people expect, and a mismeasured finished addition can quietly cost you $20,000 of credited area.
- Fix the small safety items. Missing smoke detectors, loose handrails, peeling exterior paint, and a dripping water heater are cheap to fix and expensive to have written up, especially on a VA or FHA file.
- Run the AC. In a San Antonio August, an appraiser walking into an 85 degree house is going to note the HVAC, and that note follows the file.
- Give your agent's comparable sales packet to the appraiser. Not a demand, a courtesy packet. Good appraisers use it.
What does not help: aggressive staging, new furniture, air fresheners, or being present and talking through the whole visit. Let the appraiser work.
Your Four Options When the Appraisal Comes In Low
Roughly one in ten financed San Antonio transactions sees an appraisal below contract price, and every one of them resolves through one of four doors. The lender will lend against the appraised value, not the contract price, so somebody has to cover the difference or the price has to move.
| Option | What happens | Best when |
|---|---|---|
| Renegotiate | Seller reduces price to the appraised value, or the parties split the gap. | The home has been on market a while and the seller has no better backup offer. |
| Bridge the gap | Buyer brings the shortfall in cash on top of the down payment. | Buyer has reserves and genuinely wants this specific home. |
| Dispute | Reconsideration of Value with better comparable sales, corrected square footage, or missed updates. | The appraiser used weak or distant comps, or got the measurements wrong. |
| Walk | Buyer terminates under the appraisal contingency or VA escape clause and recovers earnest money. | The gap is large, the seller will not move, and the buyer has no cash to bridge. |
The dispute path is the one people give up on too fast. A Reconsideration of Value that includes three better comparable sales, a corrected floor plan sketch, and photos of updates the appraiser did not see succeeds far more often than the internet suggests. It fails when it is just an angry email.
One structural note for sellers deciding whether to fix or discount before listing: the appraisal is where that decision gets graded. I laid out the math in sell as-is or fix first.
Frequently Asked Questions
How much does a home appraisal cost in San Antonio in 2026?
Most single-family appraisals in Bexar County run $450 to $900. Larger custom homes and rural acreage properties in Medina, Bandera, or Kendall County typically run $700 to $1,200 because comparable sales are harder to find.
Who pays for the appraisal, the buyer or the seller?
The buyer pays in nearly every San Antonio transaction, usually charged up front by the lender rather than at closing. The seller does not pay for it but is directly affected by the result, because the lender will only fund against the appraised value.
How long does an appraisal take in Bexar County?
Plan on 7 to 21 days from lender order to final report. VA appraisals in San Antonio usually come back in 7 to 12 days because the local VA appraiser panel is unusually deep. Spring is the slowest season.
What happens if the appraisal comes in below the contract price?
You have four options: renegotiate the price down, have the buyer bring the difference in cash, dispute the value through a Reconsideration of Value with better comparable sales, or terminate under the appraisal contingency. VA buyers can terminate under the VA Amendatory Escape Clause and recover earnest money.
Is a VA appraisal harder to pass than a conventional one?
It is not harder on value, but it adds Minimum Property Requirements covering safety and habitability. The items flagged most often near JBSA are peeling paint on pre-1978 homes, missing handrails, roof leaks, and non-functioning HVAC. None of those are difficult to address before the visit.
What is the Tidewater Initiative?
Tidewater is a VA process that requires the appraiser to notify the listing agent before finalizing a value below contract price. The agent then has 48 hours to submit additional comparable sales and supporting documentation. It is the best chance to influence a VA appraisal, and it only works if your agent is reachable and prepared.
Can I be present during the appraisal?
Yes, and sellers often are. Keep it brief. Hand the appraiser your documented improvement list and comparable sales packet, point out anything not visible such as a replaced sewer line or new ductwork, then let them work without narration.
Does an appraisal include a home inspection?
No. An appraisal answers what the home is worth. A home inspection answers what is wrong with it. An appraiser may note obvious defects that affect value or, on a VA or FHA file, safety, but an appraisal is never a substitute for hiring your own inspector.
Will an appraiser count my converted garage or enclosed patio?
Only if it is permitted, finished to the standard of the rest of the house, and heated and cooled. Unpermitted conversions are commonly excluded from gross living area, which is one of the most frequent causes of a surprise low value in older San Antonio neighborhoods.
Do appraisals affect my property taxes?
No. A lender appraisal is a private opinion of market value for the loan file and is not shared with the Bexar Appraisal District. Your assessed value for tax purposes is set independently by the county appraisal district.
About the Author
Christopher Beal is a U.S. Army veteran and the Owner of Veteran Real Estate San Antonio, a Beal Group practice brokered by eXp Realty (TREC License #723559). A Military Relocation Professional (MRP) and VAREP member, he is a 7-time eXp Realty ICON agent, winner of Best Real Estate Agency in the 2026 Best of San Antonio Readers' Choice (San Antonio Current, 100,000+ voters), and a 3x San Antonio Business Journal Top 25 Individual Agent (#13 in 2024, #14 in 2025, #20 in 2026). His recognition also includes 3x Platinum Top 50, 2x RateMyAgent Agent of the Year, 2x Real Producers Top 100, Five Star Professional (2026), and a RealTrends 2026 ranking. He has helped 325+ families, closed more than $125M in career volume, and holds 5.0 stars across 370+ verified reviews, working almost exclusively with military and veteran buyers and sellers across Bexar, Comal, Kendall, Medina, and Bandera counties, with a focus on VA loans, PCS moves, and homebuying near JBSA-Lackland, JBSA-Randolph, and Fort Sam Houston. He has personally submitted Tidewater comparable-sales packets that moved VA appraisals back to contract price. He can be reached at (210) 882-8583.
Talk Through Your Appraisal Before It Happens
If you are under contract, listing soon, or refinancing, the appraisal is the one step where preparation reliably changes the outcome. I will pull the actual closed comparable sales for your street, tell you honestly whether your number appraises, and build the comps packet before the appraiser ever knocks.
Call or text (210) 882-8583, or reach me at veteranrealestatesa.com. If you are weighing whether to hire an agent for this at all, FSBO vs. Realtor in San Antonio covers the tradeoff with real numbers.
Categories
- All Blogs (354)
- Alamo Heights (4)
- awards (4)
- Best Neighborhoods in San Antonio (13)
- Buyer (16)
- Buyer Education (86)
- Community Events (4)
- Hill Country (17)
- JBSA (43)
- Local Guide (6)
- Luxury (28)
- Luxury Real Estate (26)
- Market Trends (19)
- Market Update (14)
- Military Relocation (111)
- Military Retirement (3)
- Mortgage (19)
- Neighborhood Guides (18)
- neighborhoods (5)
- New Construction (16)
- PCS (42)
- Real Estate (40)
- reviews (3)
- San Antonio (53)
- San Antonio Lifestyle (4)
- San Antonio Market (5)
- San Antonio Neighborhoods (43)
- San Antonio Real Estate (100)
- San Antonio, Veterans Resources, VA Loans (5)
- Seller (55)
- VA Home Loans (30)
- VA Loans (35)
- Va Loans & Financing (27)
- Veterans (10)
- Veterans Resources (40)
Recent Posts