Selling Your San Antonio Home on PCS Orders With an Assumable VA Loan (2026)
LAST UPDATED: OCTOBER 9, 2026 | BY CHRISTOPHER BEAL, U.S. ARMY VETERAN & REALTOR
I'm Christopher Beal, a U.S. Army veteran, REALTOR (TREC License #723559) and Owner of Veteran Real Estate San Antonio, brokered by eXp Realty. More about my background.
Key Takeaways
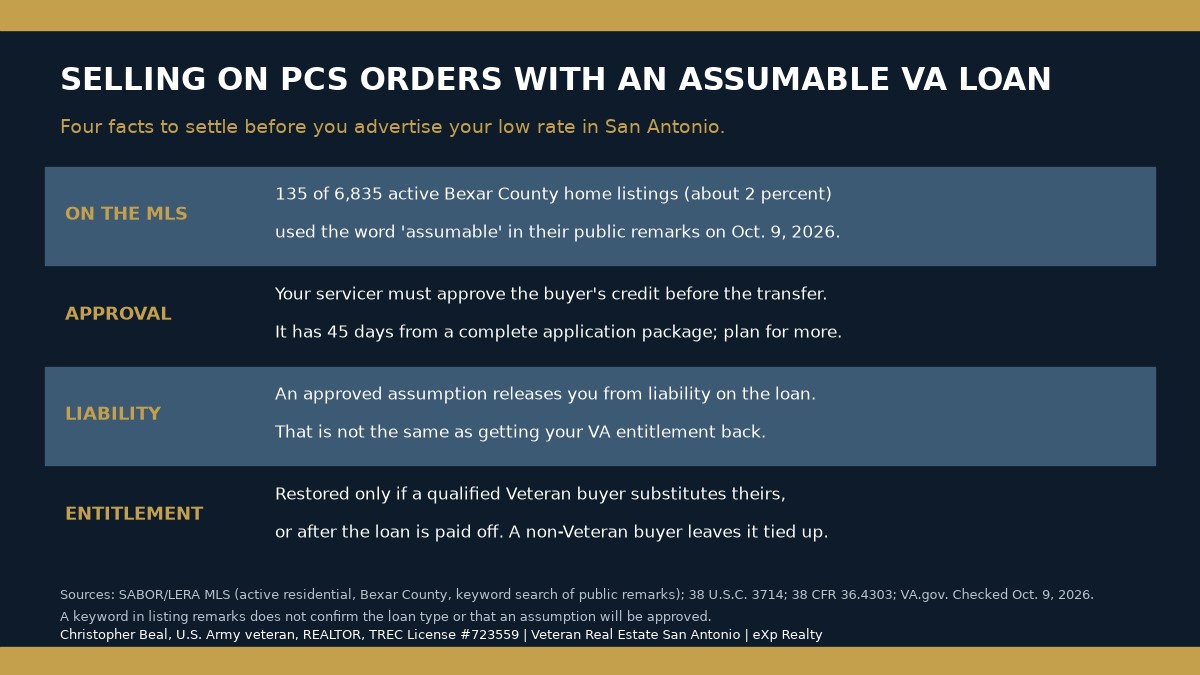
- VA loans can be assumed, but not freely. For loans made since 1988, the servicer must approve the buyer's credit before the transfer. Selling without that approval lets the holder demand the full balance.
- Release of liability and restoration of entitlement are two different things. Approval releases you from the debt; only a Veteran buyer's substitution of entitlement, or payoff of the loan, frees your entitlement.
- The buyer takes over your balance, rate and remaining term, and must bring the difference between your balance and the price. That equity gap decides who can actually buy.
- The buyer pays a VA funding fee of 0.5 percent of the loan on an assumption unless exempt, plus a servicer processing fee. Ask the servicer for an itemized estimate early.
- On October 9, 2026, 135 of 6,835 active residential listings in Bexar County (about 2 percent) used the word "assumable" in their MLS remarks.
In This Guide
How Does a VA Loan Assumption Work for the Seller?
In an assumption, the buyer takes over your existing VA loan: the same interest rate, the same remaining balance and the same remaining term. You do not pay the loan off at closing the way you would in an ordinary sale. Instead, the buyer pays you the difference between the price and the balance, and the loan stays in place with the buyer as the borrower.
The approval rule comes from federal law. For VA loans made since early 1988, 38 U.S.C. 3714 requires the loan holder (in practice, your servicer) to approve the assumption when the loan is current and the buyer qualifies on credit and agrees to take on full liability for the loan.
If the holder approves, you are relieved of further liability on the loan, including for a later default by the buyer. If you sell or transfer the home without that approval, the holder may demand immediate payment of the full balance.
The buyer does not have to be a Veteran to assume a VA loan. A civilian buyer can apply and be approved on credit. What changes with a non-Veteran buyer is your entitlement, covered next.
For the buyer's side of the same process, including the documents a servicer usually asks for, see my step-by-step VA loan assumption guide.
What Happens to Your VA Entitlement?
This is the part most sellers on PCS orders need to get right, because it affects your next purchase at the new duty station. VA lists the ways to restore entitlement on its eligibility page (updated September 22, 2026): you sold the home and the loan was paid in full; a qualified Veteran-transferee assumes your loan and substitutes their entitlement; or you repaid the loan in full without selling, which you can do only once.
| Who assumes your loan | Your liability on the loan | Your VA entitlement |
|---|---|---|
| Qualified Veteran or service member who agrees to substitute their entitlement | Released once the servicer approves the assumption | Can be restored through the substitution |
| Veteran buyer who does not substitute entitlement | Released once the servicer approves the assumption | Stays tied to this loan until it is paid off |
| Non-Veteran buyer | Released once the servicer approves the assumption | Stays tied to this loan until it is paid off |
Source: 38 U.S.C. 3714 and VA.gov eligibility page, checked October 9, 2026. Applies to VA-guaranteed loans requiring approval of the assumption.
Entitlement that stays tied to the assumed loan does not always stop you from using a VA loan again. VA notes that you may still have remaining entitlement to buy another home. How much a lender will lend without a down payment then depends on your remaining entitlement and the county loan limit where you buy. Request an updated Certificate of Eligibility and have your next lender run the numbers before you accept a non-Veteran buyer's offer.
If you are still deciding whether to sell at all, my keep, sell or rent decision framework walks through that choice first.
The Equity Gap: A Worked Example
The low rate only helps a buyer who can pay you the difference between your loan balance and the price. That difference is usually cash, or a separate second loan if the buyer can find a lender willing to make one behind a VA first lien. The example below is illustrative, not a quote for any home or buyer.
| Illustrative input or result | Amount |
|---|---|
| Original VA loan (2021), 30-year fixed at 3.00 percent | $300,000 |
| Balance after 60 monthly payments (25 years left) | about $266,700 |
| Assumed principal and interest payment | about $1,265 a month |
| New 30-year loan on the same $266,700 at 7.40 percent | about $1,847 a month |
| Monthly difference on the same principal | about $582 |
| Sale price, if the home is worth $330,000 | $330,000 |
| Equity gap the buyer must cover | about $63,300, plus the buyer's closing costs |
Illustrative only. Standard amortization arithmetic, principal and interest only (taxes, insurance and any HOA dues are extra). The 7.40 percent figure is Freddie Mac's Primary Mortgage Market Survey national average for a 30-year fixed loan in the week of October 8, 2026. It is a conventional benchmark, not a VA rate or a quote; a buyer's actual rate depends on the loan type, credit and lender.
Two things follow from the math. First, the rate advantage is real for a buyer who has the cash: on the same principal the assumed payment is several hundred dollars a month lower. Second, the larger your equity, the smaller your pool of buyers, because fewer buyers can bring a large gap. A seller who bought in 2021 and owes most of the value has an easier assumption sale than one who has paid the loan down or seen large appreciation.
Who Pays What on an Assumption?
Keep these cost categories separate, because they come from different rules.
- VA funding fee (buyer). VA's funding fee page (updated October 5, 2026) lists 0.5 percent of the loan amount for an assumption. In the example above that is about $1,334. Buyers who receive VA disability compensation, and the other groups VA lists, are exempt. My VA funding fee guide covers the exemptions.
- Servicer processing fee (buyer). VA regulations at 38 CFR 36.4313 limit what the holder may charge to process an assumption, and VA has issued guidance on allowable amounts since then. Do not assume a single dollar figure; ask your servicer for its current itemized assumption fees before you list.
- Ordinary closing costs. Title, escrow, recording and similar costs still apply. Who pays which ones is negotiated in the contract, as in any sale.
- Your selling costs. Your payoff is replaced by the buyer's equity payment to you, but your other costs of sale, such as commissions you agree to, title items you agree to pay and prorated taxes, still apply.
Fitting an Assumption Into a PCS Timeline
Under 38 CFR 36.4303, the holder must decide on the buyer's creditworthiness and notify you no later than 45 days after it receives a complete application package. That clock can be extended by documented delays outside the holder's control, such as an employer that is slow to verify income, and it does not start until the package is complete. Then closing still has to be scheduled. Treat 45 days as the shortest realistic review window, not the whole timeline.
| Your situation | What to weigh |
|---|---|
| Several months before your report date, small equity, low rate | The strongest case for advertising the assumption. Call your servicer first to confirm the loan is assumable, current and how it handles assumption packages. |
| Large equity | Fewer buyers can cover the gap. Consider accepting both assumption and ordinary financing offers so you are not limited to cash-heavy buyers. |
| You plan to use a VA loan at your next duty station soon | Check your remaining entitlement with your next lender before accepting a non-Veteran buyer. A Veteran buyer who substitutes entitlement avoids the problem. |
| Only weeks before you leave | An assumption can still close after you move, with remote signing, but the review time is outside your control. Compare it with an ordinary sale using my remote seller playbook. |
None of these is a rule for every seller. Your payment history, equity, next-assignment plans and the buyer's finances decide which path makes sense, and I can lay the options side by side for your address. I am a REALTOR, not a lender or financial advisor, so confirm loan terms with your servicer and your next lender.
How Often Do San Antonio Sellers Advertise an Assumable Loan?
I searched the SABOR/LERA MLS on October 9, 2026. Of 6,835 active residential listings in Bexar County, 135 (about 2 percent) used the word "assumable" in their public remarks. Their median list price was $309,000. Ninety-one of the 135 also mentioned VA somewhere in the remarks.
Source: SABOR/LERA MLS, active status, residential property type, Bexar County, keyword search of public remarks, complete pagination, pulled October 9, 2026. A keyword match does not confirm the loan type, that the loan is current, or that a servicer will approve an assumption, and some listings mention assumable financing without using that word.
The practical point: an assumable low-rate loan is still uncommon among San Antonio listings, so when it fits, it can help a listing stand out to buyers who have cash for the gap.
Pricing and Marketing the Listing
An assumable rate does not change what the house is worth to an appraiser or to a buyer using new financing. Price against recent comparable sales, then let the payment difference make the listing more competitive. If a buyer offers more because of the rate, that extra is part of the equity gap they must fund, and it is a negotiation, not a formula.
- Before listing: get your current payoff and an assumption information packet from your servicer, confirm the loan is current, and ask for its itemized assumption fees and typical processing time.
- In the listing: state the rate, approximate balance and remaining term only after you have confirmed them, and say that the assumption is subject to servicer approval.
- With offers: ask buyers who plan to assume for proof of the cash or financing to cover the gap, and whether they will substitute VA entitlement.
- In the contract: make the assumption approval a stated condition with a realistic timeline, and decide in advance what happens if approval is denied or delayed.
Buyers looking for these homes often start from the other side of the same question; my buyer's guide to assumable VA loans in San Antonio shows what they will ask you.
About the Author: Christopher Beal
Christopher Beal is a U.S. Army veteran and the Owner of Veteran Real Estate San Antonio, a Beal Group practice brokered by eXp Realty (TREC License #723559). A Military Relocation Professional (MRP) and VAREP member, he is a 7-time eXp Realty ICON agent, winner of Best Real Estate Agency in the 2026 Best of San Antonio Readers' Choice (San Antonio Current, 100,000+ voters), and a 3x San Antonio Business Journal Top 25 Individual Agent (#13 in 2024, #14 in 2025, #20 in 2026).
His recognition also includes 3x Platinum Top 50, 2x RateMyAgent Agent of the Year, 2x Real Producers Top 100, Five Star Professional (2026), and a RealTrends 2026 ranking. He has helped 325+ families, closed more than $125M in career volume, and holds 5.0 stars across 370+ verified reviews, working almost exclusively with military and veteran buyers and sellers across Bexar, Comal, Kendall, Medina, and Bandera counties, with a focus on VA loans, PCS moves, and homebuying near JBSA-Lackland, JBSA-Randolph, and Fort Sam Houston.
If you are selling on PCS orders with a low-rate VA loan, he will run the equity-gap and entitlement numbers for your address before you decide how to list. He can be reached at (210) 882-8583.
Frequently Asked Questions
Is my VA loan assumable?
VA-guaranteed loans can be assumed, and for loans made since early 1988 the servicer must approve the buyer's credit first under 38 U.S.C. 3714. The loan generally needs to be current. Call your servicer to confirm your loan's status and its assumption process.
Can a non-Veteran buy my home and assume my VA loan?
Yes, if the servicer approves the buyer's credit. You are released from liability on the loan once the assumption is approved, but your VA entitlement stays tied to that loan until it is paid off, because only a Veteran buyer can substitute entitlement.
Will I get my VA entitlement back after an assumption?
Only if a qualified Veteran buyer assumes the loan and agrees to substitute their entitlement for yours, or once the loan is paid in full. Otherwise you may still have remaining entitlement; request an updated Certificate of Eligibility and ask your next lender what it allows.
How long does a VA loan assumption take?
The servicer must decide no later than 45 days after it receives a complete application package (38 CFR 36.4303), and documented delays outside its control can extend that. Assembling the package and scheduling closing add time, so plan for longer than 45 days.
What does the buyer pay to assume a VA loan?
The VA funding fee on an assumption is 0.5 percent of the loan amount unless the buyer is exempt, for example because they receive VA disability compensation. The servicer also charges a processing fee, and ordinary closing costs apply. Ask the servicer for current itemized fees.
What if the buyer cannot cover the equity gap?
Then the assumption usually does not work for that buyer. Some buyers find a second loan for part of the gap, but availability is limited and the servicer and lenders involved must agree. Many sellers accept offers with ordinary financing as well, so the sale does not depend on one path.
Does Serve & Save apply when I sell?
No. Serve & Save is a buyer program: when you buy your next home with me as your buyer's agent, it reduces your closing costs by 1 percent of the gross buyer's agent commission for each verified year of active service, subject to lender approval. Details are on the Serve & Save page.
Explore More Resources
- Military Relocation
- Free Home Evaluation
- VA Home Loans
- Serve & Save Program
- Client Reviews
- About Christopher
Call or text Christopher Beal at (210) 882-8583 with your address, your approximate loan balance and your report date, and I will lay out the assumption and ordinary-sale options side by side, starting with a home evaluation.
Categories
- All Blogs (358)
- Alamo Heights (4)
- awards (4)
- Best Neighborhoods in San Antonio (13)
- Buyer (16)
- Buyer Education (92)
- Community Events (4)
- Hill Country (17)
- JBSA (49)
- Local Guide (6)
- Luxury (28)
- Luxury Real Estate (26)
- Market Trends (19)
- Market Update (13)
- Military Relocation (116)
- Military Retirement (3)
- Mortgage (20)
- Neighborhood Guides (19)
- neighborhoods (5)
- New Construction (16)
- PCS (44)
- Real Estate (40)
- reviews (3)
- San Antonio (52)
- San Antonio Lifestyle (4)
- San Antonio Market (5)
- San Antonio Neighborhoods (45)
- San Antonio Real Estate (98)
- San Antonio, Veterans Resources, VA Loans (5)
- Seller (55)
- VA Home Loans (30)
- VA Loans (38)
- Va Loans & Financing (27)
- Veterans (10)
- Veterans Resources (40)
Recent Posts