JBSA House Hacking With a VA Loan (2026): Duplexes and Fourplexes Near Randolph in Schertz, Cibolo and Universal City
LAST UPDATED: OCTOBER 11, 2026 | BY CHRISTOPHER BEAL, U.S. ARMY VETERAN & REALTOR
I'm Christopher Beal, a U.S. Army veteran, REALTOR (TREC License #723559) and Owner of Veteran Real Estate San Antonio, brokered by eXp Realty. More about my background.
Key Takeaways
- VA purchase loans cover homes of up to four units. You must certify that you intend to live in the property as your home, and on active duty your spouse can meet that requirement if your service keeps you away.
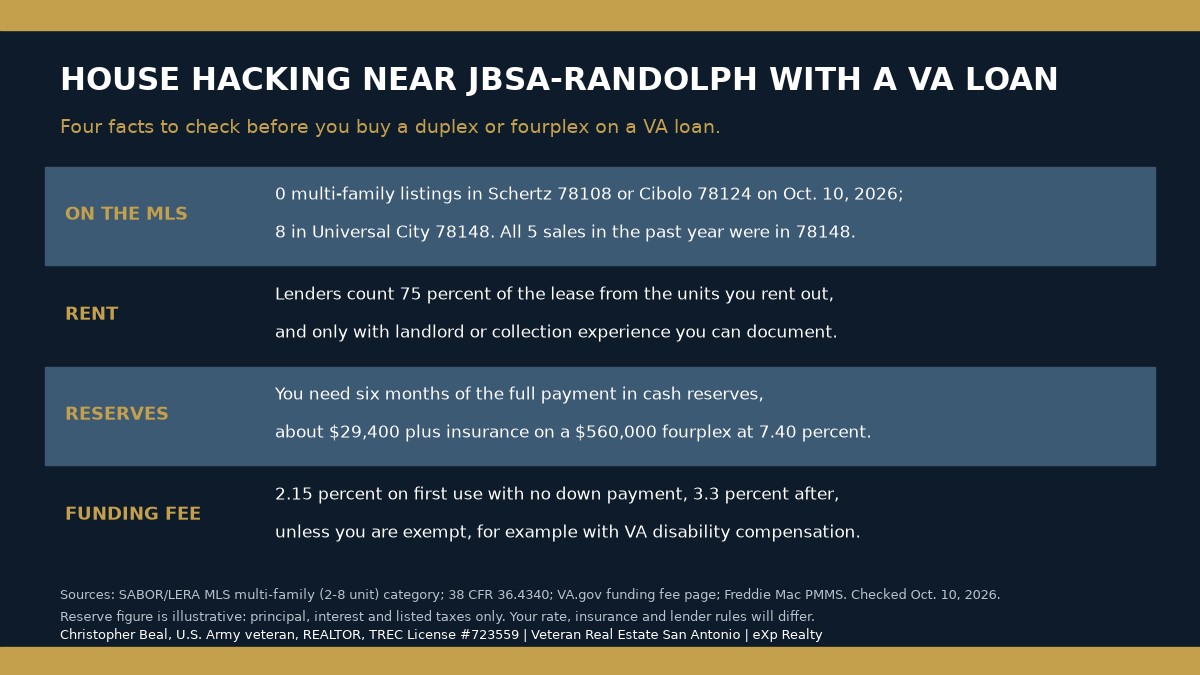
- Rent from the other units helps you qualify only at 75 percent of the lease, only with documented landlord or collection experience, and only if you have six months of principal, interest, taxes and insurance in reserve.
- Those reserves are the real cash hurdle. On the worked example below, a $560,000 fourplex, six months of payments comes to roughly $29,400 before insurance.
- The funding fee is 2.15 percent of the loan on first use with less than 5 percent down and 3.3 percent after first use, unless you are exempt, for example because you receive VA disability compensation.
- Near Randolph, 2-4 unit homes on the MLS are almost all in Universal City. Schertz and Cibolo had none listed on October 10, 2026 and no multi-family MLS sales in the past twelve months.
In This Guide
What Does the VA Allow on a 2-4 Unit Home?
VA's purchase loan page (updated January 7, 2026) says the loan can buy a single-family home of up to four units, as long as you will live in the home you are buying. A duplex, triplex or fourplex where you live in one unit and rent the others is the same loan program you would use for a single-family house.
The occupancy rule comes from 38 U.S.C. 3704(c). You certify, when you apply and again at closing, that you intend to occupy the property as your home, and the requirement is met if you do move in within a reasonable time after closing. The statute does not set a minimum number of months you must stay.
What it requires is honest intent at the time you buy: buying a fourplex you never plan to live in is not a VA loan.
For active-duty buyers, the same section adds a practical exception. If your service prevents you from living in the home, the requirement is still met when your spouse occupies it, or intends to, and makes the certification. A dependent child can also satisfy it through an attorney-in-fact or legal guardian. That matters for a JBSA buyer who closes just before a deployment or a temporary duty assignment.
Your lender's loan documents and occupancy certification are what you actually sign, so read them before closing and ask the lender how it handles a move-in date that depends on your report date.
How Do Lenders Count Rent From the Other Units?
This is where most "tenants pay your mortgage" pitches skip a step. VA's underwriting regulation, 38 CFR 36.4340(f)(12), sets three conditions before projected rent from the units you will not live in can help you qualify:
- 75 percent of the lease. The rental income used in the loan analysis is 75 percent of the amount on the lease or rental agreement, unless a higher percentage can be documented.
- A reasonable likelihood of success as a landlord. The lender bases this on documentation of prior experience managing rental units or other collection activities. A first-time landlord with no such history may find the rent is not counted at all.
- Six months of reserves. You must have verified cash reserves to make the full payment (principal, interest, taxes and insurance) for at least six months without help from the rental income.
Lenders can add their own requirements on top of the regulation, so ask each lender in writing how it will treat the rent, what leases or appraisal rent estimates it needs, and what it will accept as landlord experience. A lender who has closed VA loans on 2-4 unit homes before will answer those questions quickly.
Entitlement: How Much Can You Borrow With No Down Payment?
If you have full entitlement, VA's loan limits page says there is no VA county limit on the loan, but full entitlement does not mean you can borrow any amount. The lender still approves the loan on your credit, income, debts and assets, and the loan cannot exceed the lower of the appraised value or the price.
If you already have a VA loan open, for example on a house you kept at your last duty station, you have remaining entitlement, and the county limit comes into play. VA's method uses the county's one-unit conforming limit from FHFA, even when you are buying a fourplex:
- Take the county's one-unit limit. For 2026, FHFA's baseline one-unit limit is $832,750, which is the figure that applies in Bexar and Guadalupe counties.
- Multiply by 25 percent: $208,187.50.
- Subtract the entitlement already charged on your Certificate of Eligibility. With $50,000 already in use, $158,187.50 remains.
- Most lenders want entitlement plus any down payment to cover 25 percent of the loan, so $158,187.50 supports a loan of about $632,750 with no down payment. A larger loan is possible with a down payment, if the lender approves.
The 2025 limit of $806,500 that circulated in older guides is out of date. Pull a current Certificate of Eligibility before you shop so you know which case you are in.
What Is the Funding Fee on a Multi-Unit Purchase?
The funding fee works the same way on a fourplex as on a single-family home. VA's funding fee page (updated October 5, 2026) lists these purchase rates, which apply equally to Veterans, active-duty service members and National Guard and Reserve members:
| Down payment | First use | After first use |
|---|---|---|
| Less than 5% | 2.15% | 3.3% |
| 5% or more | 1.5% | 1.5% |
| 10% or more | 1.25% | 1.25% |
You do not pay the fee if you receive VA compensation for a service-connected disability, are eligible for that compensation but receive retirement or active-duty pay instead, are a surviving spouse receiving Dependency and Indemnity Compensation, have a proposed or memorandum rating before closing that finds you eligible for compensation based on a pre-discharge claim, or are on active duty and show evidence of a Purple Heart on or before closing. There is no separate 10 percent rating threshold. The fee can be paid at closing or financed into the loan; on the $560,000 example below, 2.15 percent is $12,040. My VA funding fee guide covers the exemptions in more detail.
What 2-4 Unit Homes Are Actually for Sale Near Randolph?
Schertz, Cibolo and Universal City are the usual short list for a Randolph commute, but they are not equal for house hacking. I pulled every listing in the SABOR/LERA MLS multi-family (2-8 unit) category in the three ZIP codes on October 10, 2026, plus every closed multi-family sale in the twelve months before that date.
| ZIP code | Listed for sale, Oct. 10, 2026 | Closed sales, Oct. 10, 2025 to Oct. 10, 2026 |
|---|---|---|
| 78108 Schertz | 0 | 0 |
| 78124 Cibolo | 0 | 0 |
| 78148 Universal City | 8 (1 duplex at $199,900; 7 fourplexes from $476,000 to $675,000; 1 of the 8 under option) | 5 (a duplex at $210,000; fourplexes at $415,000, $450,000, $640,000 and $659,000) |
Source: SABOR/LERA MLS, multi-family (2-8 unit) property type, active and option statuses on October 10, 2026, and closings dated October 10, 2025 or later. Excludes homes listed under another property type and off-market sales.
Three things stand out. First, the Universal City fourplexes cluster in two groups: older buildings from 1983 to 2004 around Meadow Oaks listed from $476,000 to $560,000, and 2007 townhome-style fourplexes around Mathom Landing listed from $629,000 to $675,000. Second, listed annual property taxes on the fourplexes ran from about $10,300 to $13,600, which is a large part of the monthly payment and of the six-month reserve. Third, several of these listings had been on the market for months, which gives a prepared buyer room to negotiate repairs or closing costs.
In Schertz and Cibolo, the realistic version of house hacking on a VA loan is usually a single-family home where you rent a room or a separate living area. Ask your lender before you count on that rent: the 2-4 unit rule above is written for separate dwelling units, and a room rental is not the same thing. For the neighborhoods themselves, see my Schertz guide and Cibolo guide, and living near Randolph AFB for the commute picture.
A Worked Example: $560,000 Fourplex, First Use, No Down Payment
This is an illustration, not a quote. It uses a list price and tax figure from the October 10, 2026 MLS pull, the Freddie Mac Primary Mortgage Market Survey 30-year average of 7.40 percent for the week of October 8, 2026 as a stand-in rate (it is a conventional benchmark; your VA rate will differ), and rents of $1,250 per unit, the figure one Universal City fourplex listing reported for its leased units.
| Line item | Amount |
|---|---|
| Price and base loan | $560,000 |
| Funding fee, 2.15% (financed) | $12,040 |
| Total loan | $572,040 |
| Principal and interest, 30 years at 7.40% | about $3,961 per month |
| Property tax ($11,319 a year as listed) | about $943 per month |
| Payment before insurance | about $4,904 per month, plus a landlord insurance quote |
| Lease rent on three units | $3,750 per month |
| Rent the lender may count (75%) | $2,812.50 per month, if you meet the landlord-success test |
| Six months of reserves | about $29,400, plus six months of insurance |
Illustrative only. Rate, insurance, taxes after purchase, rents and vacancy will differ. Closing costs are not included.
Read that table from the bottom up. The down payment can be zero, but you still need around $30,000 or more in verified reserves, closing costs, and enough income to carry roughly $2,100 a month plus insurance beyond the rent the lender counts. On a smaller duplex the numbers shrink, but so do the rents. Run your own numbers with a lender before you write an offer.
Leases, Military Tenants and the SCRA
Near Randolph, many of your tenants will be service members. Plan your lease around the Servicemembers Civil Relief Act, 50 U.S.C. 3955. A service member tenant who receives permanent change of station orders, or deployment orders of 90 days or more, can end a residential lease with written notice and a copy of the orders.
On a month-to-month rent schedule, termination takes effect 30 days after the next rent due date following the notice. Build that possibility into your vacancy budget rather than treating it as a surprise.
Screen every applicant with the same written criteria, in line with fair housing law, and check how the JBSA-Randolph housing office refers off-base rentals before you list.
When Orders Move You
When you PCS out, you can generally keep the property and rent all of the units; VA's rule is about your intent to occupy when you buy. Two things follow you to the next duty station:
- Entitlement. The entitlement on this loan stays in use until the loan is paid off or a qualified Veteran buyer later assumes it and substitutes their own. Your next VA purchase runs on remaining entitlement, using the math above.
- Management and taxes. Managing four units from another state is a real job. My guides on becoming a landlord after a PCS and self-managing versus hiring a property manager cover both. Under IRS Publication 527, while you live in one unit you divide expenses between the rental and personal parts and depreciate only the rental part; talk with a tax professional before you file.
If you are still planning the move itself, start with my PCS to San Antonio guide.
Does Serve & Save Apply to a House Hack?
Yes, if you buy with me as your buyer's agent. Serve & Save reduces your closing costs by 1 percent of the gross buyer's agent commission for each verified year of active service, subject to lender approval. It is a closing-cost reduction, not a fixed dollar amount, and your lender decides how much credit the loan can accept.
About the Author
Christopher Beal is a U.S. Army veteran and the Owner of Veteran Real Estate San Antonio, a Beal Group practice brokered by eXp Realty (TREC License #723559). A Military Relocation Professional (MRP) and VAREP member, he is a 7-time eXp Realty ICON agent, winner of Best Real Estate Agency in the 2026 Best of San Antonio Readers' Choice (San Antonio Current, 100,000+ voters), and a 3x San Antonio Business Journal Top 25 Individual Agent (#13 in 2024, #14 in 2025, #20 in 2026).
His recognition also includes 3x Platinum Top 50, 2x RateMyAgent Agent of the Year, 2x Real Producers Top 100, Five Star Professional (2026), and a RealTrends 2026 ranking. He has helped 325+ families, closed more than $125M in career volume, and holds 5.0 stars across 370+ verified reviews, working almost exclusively with military and veteran buyers and sellers across Bexar, Comal, Kendall, Medina, and Bandera counties, with a focus on VA loans, PCS moves, and homebuying near JBSA-Lackland, JBSA-Randolph, and Fort Sam Houston.
If you are weighing a duplex or fourplex near Randolph, he will pull the current multi-family listings and walk through the rent, reserve and entitlement math with you and your lender before you write an offer. He can be reached at (210) 882-8583.
Frequently Asked Questions
Can I buy a fourplex with a VA loan and no down payment?
Yes, if you will live in one unit as your home, the lender approves you, and your entitlement covers the loan. With full entitlement there is no VA county limit; with remaining entitlement the county's one-unit limit sets how much you can borrow with nothing down.
Does rent from the other units count toward qualifying?
It can. Under 38 CFR 36.4340 the lender uses 75 percent of the lease amount, but only if you show a reasonable likelihood of success as a landlord, based on prior experience managing rentals or other collection work, and have six months of reserves to make the payment without the rent.
How long do I have to live in the property?
The VA statute, 38 U.S.C. 3704(c), requires you to certify that you intend to occupy the home and to move in within a reasonable time after closing. It does not set a minimum number of months. Your lender's occupancy certification is what you sign, so read it and ask how it handles your report date.
What if I am deployed when the loan closes?
If your active-duty service keeps you from living in the home, the occupancy requirement is still met when your spouse occupies or intends to occupy it and signs the certification.
What is the funding fee on a multi-unit VA loan?
The same as on a single-family home: 2.15 percent of the loan on first use with less than 5 percent down, 3.3 percent after first use, and lower rates with a down payment. You are exempt if, for example, you receive VA compensation for a service-connected disability or are on active duty with a Purple Heart.
Are there duplexes for sale in Schertz or Cibolo?
None were listed in the MLS multi-family category on October 10, 2026, and none sold in that category in the prior twelve months. Universal City had eight listings and all five of the area's multi-family sales.
Can my tenant break the lease if they get orders?
Yes. Under the SCRA, a service member tenant with permanent change of station orders or deployment orders of 90 days or more can end the lease with written notice and a copy of the orders. On monthly rent, it ends 30 days after the next rent due date.
Does Serve & Save work on a duplex or fourplex?
Yes, when you buy with me as your buyer's agent. It reduces your closing costs by 1 percent of the gross buyer's agent commission for each verified year of active service, subject to lender approval. Details are on the Serve & Save page.
Explore More Resources
- Military Relocation
- Free Home Evaluation
- VA Home Loans
- Serve & Save Program
- Client Reviews
- About Christopher
Call or text Christopher Beal at (210) 882-8583 with your report date, your Certificate of Eligibility status and the price range you are considering, and I will send you the current 2-4 unit listings near Randolph with the reserve math for each.
Categories
- All Blogs (357)
- Alamo Heights (4)
- awards (4)
- Best Neighborhoods in San Antonio (13)
- Buyer (16)
- Buyer Education (91)
- Community Events (4)
- Hill Country (17)
- JBSA (49)
- Local Guide (6)
- Luxury (28)
- Luxury Real Estate (26)
- Market Trends (19)
- Market Update (13)
- Military Relocation (115)
- Military Retirement (3)
- Mortgage (20)
- Neighborhood Guides (19)
- neighborhoods (5)
- New Construction (16)
- PCS (44)
- Real Estate (40)
- reviews (3)
- San Antonio (52)
- San Antonio Lifestyle (4)
- San Antonio Market (5)
- San Antonio Neighborhoods (45)
- San Antonio Real Estate (98)
- San Antonio, Veterans Resources, VA Loans (5)
- Seller (55)
- VA Home Loans (30)
- VA Loans (37)
- Va Loans & Financing (27)
- Veterans (10)
- Veterans Resources (40)
Recent Posts